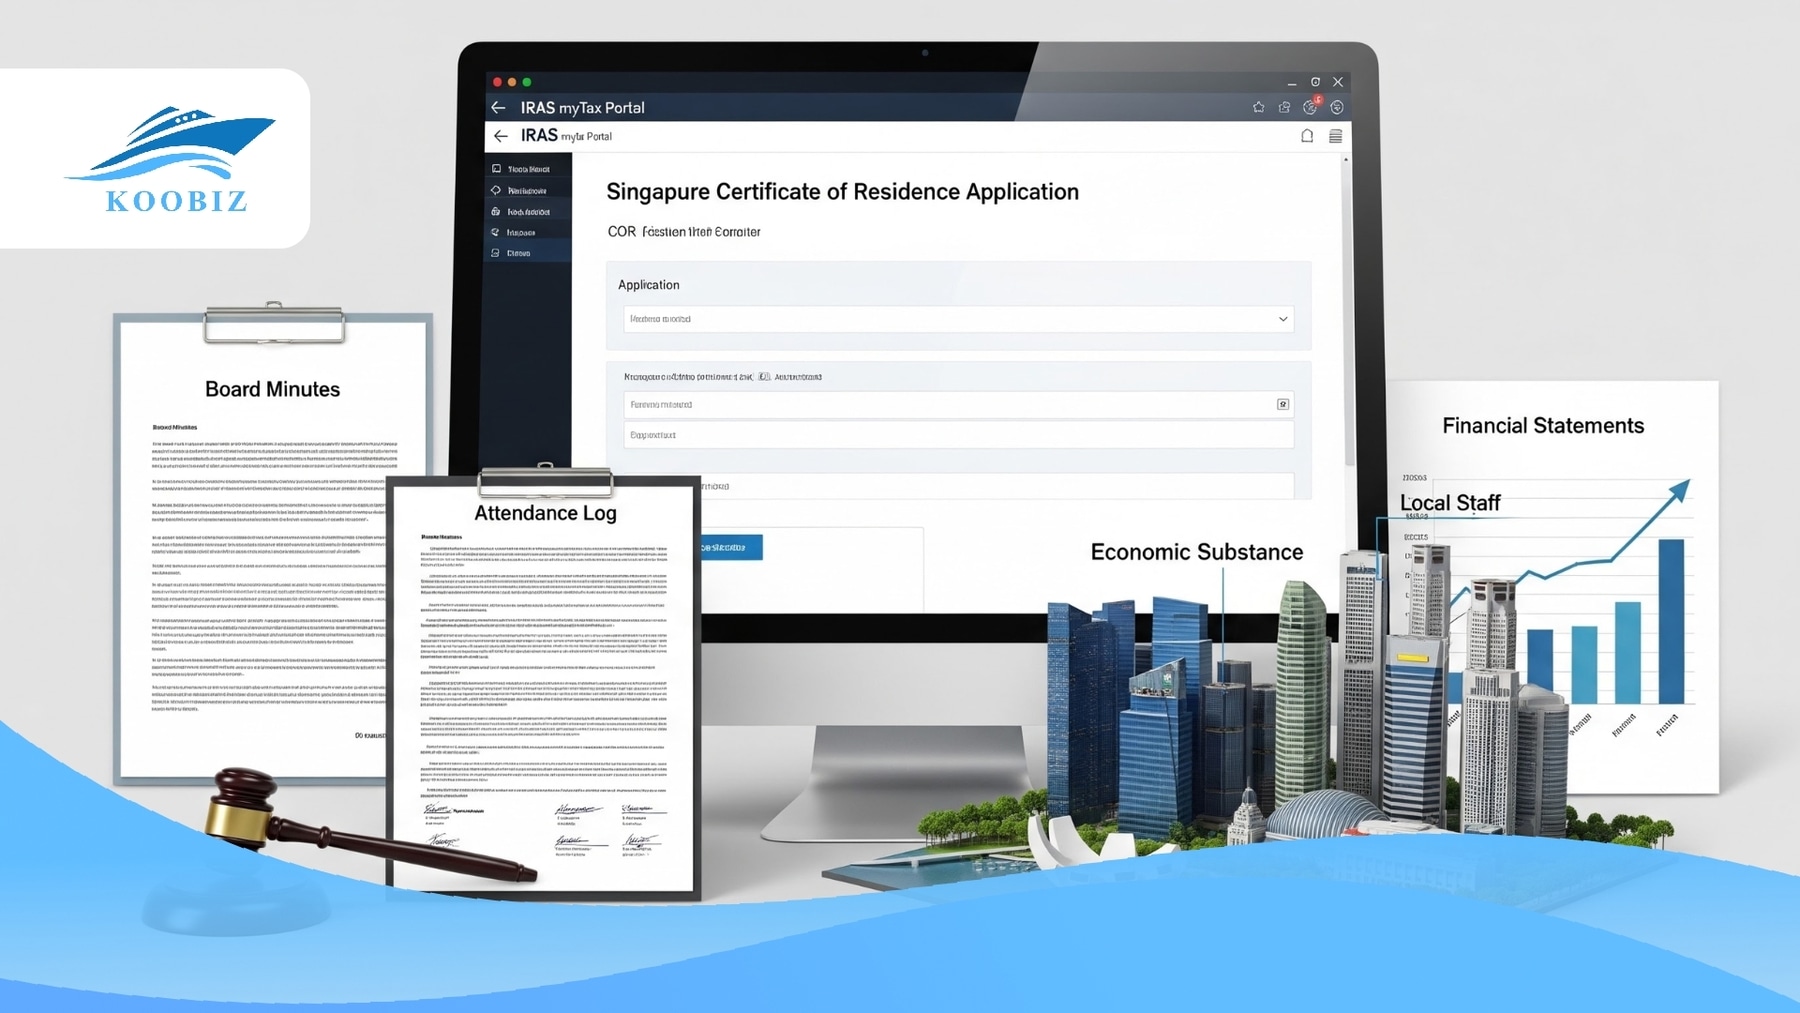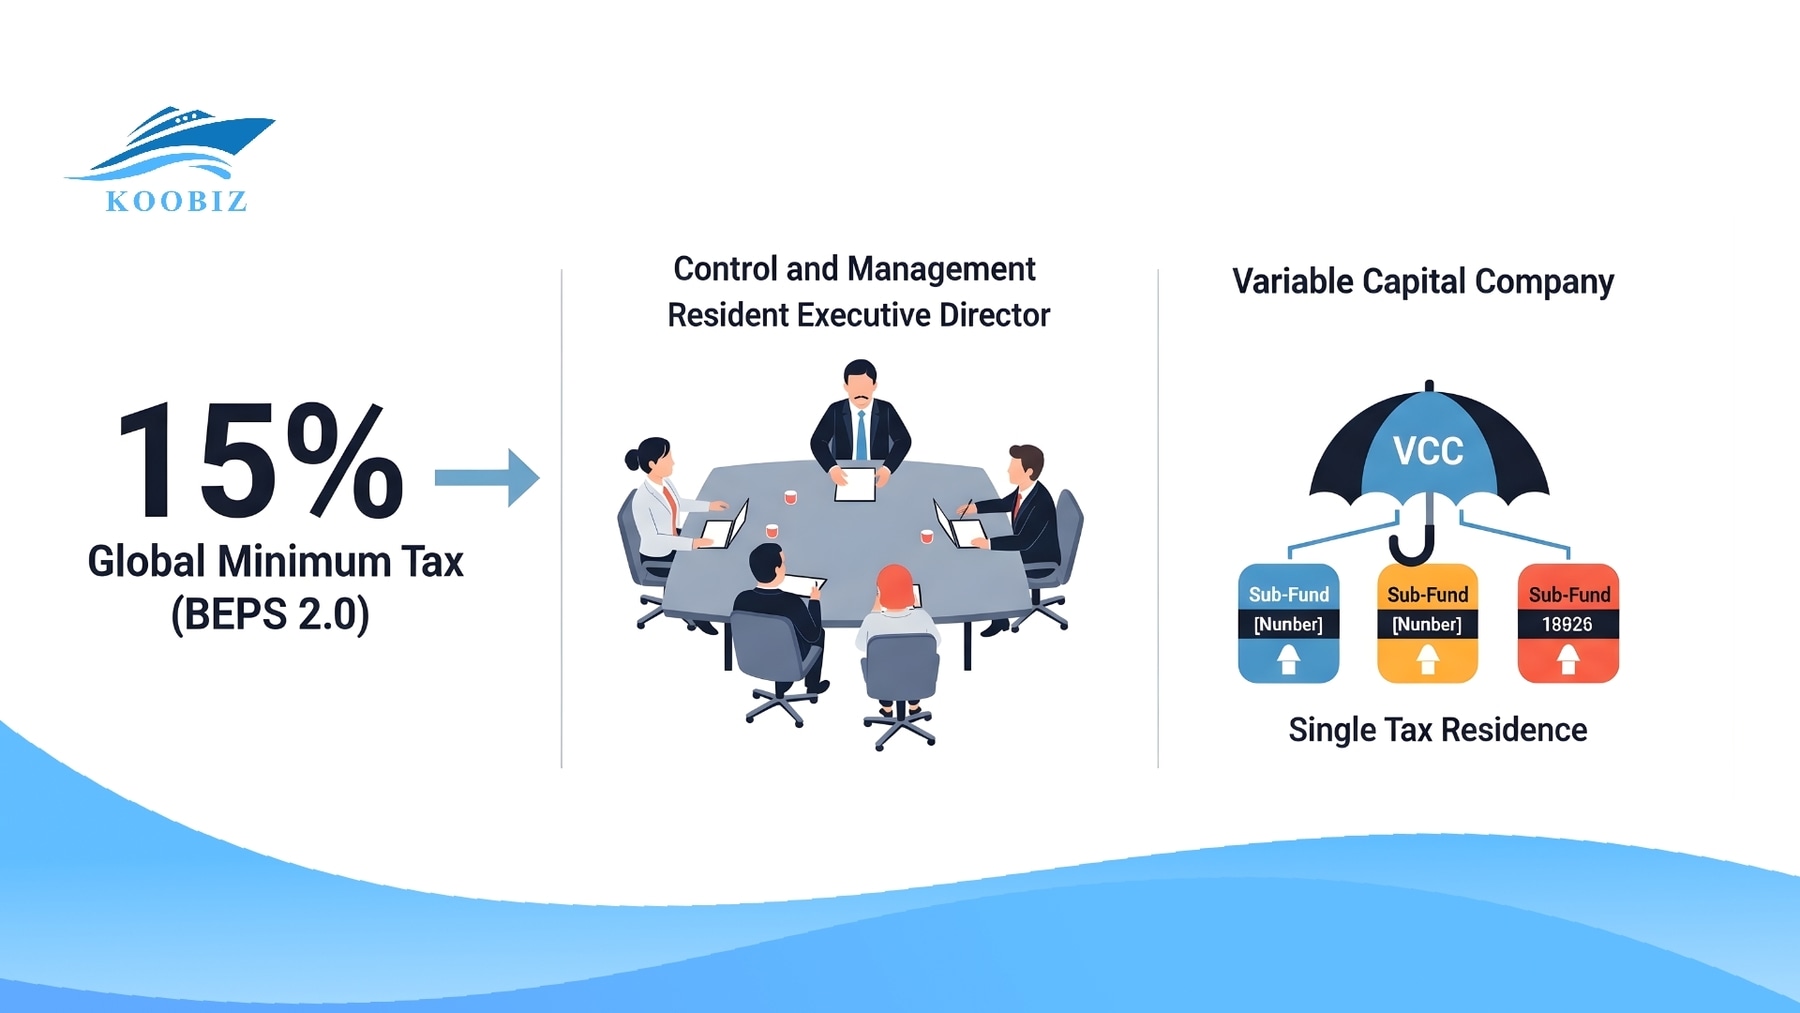
Category: Taxation & GST

  • File ECI in Singapore: How to File Estimated Chargeable Income Correctly

    File ECI in Singapore: How to File Estimated Chargeable Income Correctly

    [SUMMARIES]

    Singapore companies must file Estimated Chargeable Income (ECI) within three months of their financial year-end unless eligible for a waiver.

    Early filing secures interest-free payment installments, while late submission triggers penalties and immediate tax demands.

    ECI is a mandatory preliminary tax estimate distinct from the final Corporate Income Tax Return and is vital for compliance.

    [/SUMMARIES]

    Discover how businesses in Singapore can file their Estimated Chargeable Income (ECI) correctly and on time. This guide explains what ECI is, who needs to file, important deadlines, common mistakes to avoid, and how professional support from Koobiz can make the process simple, accurate, and stress-free.

    What Is Estimated Chargeable Income (ECI)?

    Estimated Chargeable Income (ECI) is an estimate of your company’s taxable profits for a specific Year of Assessment (YA) in Singapore. It reflects your projected taxable income after allowable expenses but before applying tax incentives such as Partial Tax Exemption (PTE) or Start-Up Tax Exemption (SUTE).

    ECI is a key part of Singapore’s corporate tax system. It allows the Inland Revenue Authority of Singapore (IRAS) to assess tax liabilities early—well before the final corporate tax return (Form C, C-S, or C-S Lite) is submitted. This helps both the tax authority and businesses manage cash flow and tax obligations efficiently.

    All Singapore-incorporated companies must submit their ECI within 3 months after the end of the financial year, unless they qualify for an ECI filing waiver, regardless of profit or loss.

    Who Needs to File ECI in Singapore?
    Know if your company must file ECI
    Know if your company must file ECI

    Most Singapore-incorporated companies must file their Estimated Chargeable Income (ECI), even if they made no profit. Filing ECI allows IRAS to estimate your tax early and helps you plan cash flow.

    1. Filing Requirement

    • Active companies, including subsidiaries and foreign branches.
    • Dormant companies or those with nil profits, unless granted a waiver.

    2. ECI Filing Waiver

    You do not need to file ECI if both conditions are met:

    • Annual revenue ≤ SGD 5 million.
    • ECI is nil for the Year of Assessment (before exemptions).

    Examples

    Revenue ECI Need to File?
    $5M $100,000 Yes
    $10M Nil Yes
    $5M Nil No

    Key Point: Missing the filing deadline may lead IRAS to estimate your tax, which could be higher. Filing on time ensures compliance and avoids penalties.

    When Do Companies Need to File ECI?

    In Singapore, companies must file their Estimated Chargeable Income (ECI) within three months after the end of their financial year (FYE).

    IRAS usually sends a reminder via the myTax Portal, but the legal responsibility to file on time lies with the company. Even without a notification, submission must be completed by the deadline unless an administrative waiver applies.

    Example: For a FYE of 31 December, the ECI must be filed by 31 March the following year.

    Timely filing keeps your company compliant and prevents IRAS from issuing an estimated Notice of Assessment (NOA), which may result in higher provisional taxes and immediate payment demands.

    Why Companies Should File ECI Early: Benefits and GIRO Installment Plan
    File ECI early for smoother payments
    File ECI early for smoother payments

    Filing your Estimated Chargeable Income (ECI) early is a smart financial strategy. It allows your company to maximize the number of interest-free GIRO installments, spreading your tax payments and improving cash flow predictability.

    GIRO Installments by Filing Timeline

    Filing Timeline (After FYE) Maximum GIRO Installments
    Within 1 month 10
    Within 2 months 8
    Within 3 months 6
    After 3 months 0 (full payment required)

    Note: Minimum monthly deduction is S$50, and a GIRO arrangement with IRAS is required.

    Example: Company A (FYE 31 December, Tax S$10,000)

    Scenario Filing Date Payment Scheme Deduction Details
    Early Filing 26 Jan 10 Installments S$1,000/month (Feb–Nov)
    Standard Filing 26 Mar 6 Installments S$1,666/month (Apr–Sept)
    Late Filing After 31 Mar Lump Sum S$10,000 (full payment)

    Key Takeaways:

    • Filing within 1 month after FYE gives maximum flexibility.
    • Early filing spreads out payments, easing cash flow.
    • Avoids estimated NOA from IRAS, which can result in higher provisional taxes.

    How to File ECI with IRAS

    Filing your Estimated Chargeable Income (ECI) is a streamlined digital process conducted through the IRAS myTax Portal. To ensure a smooth submission, your company must have its digital credentials and financial data prepared in advance.

    Where to File ECI (IRAS myTax Portal)

    All ECI submissions must be completed online. Before logging in, ensure the following:

    • Portal: Access via myTax Portal.
    • Identity: Log in using your Singpass.
    • Authorization: The person filing (Director, Employee, or Tax Agent) must be authorized as a “Corporate Tax (Filing and Applications)” user via the Corppass system.
    • Entity Details: Have your Company UEN (Unique Entity Number) and Entity ID ready.

    Information Required for ECI Filing

    To ensure accuracy and avoid future discrepancies with your final tax return (Form C/C-S), prepare these figures:

    • Revenue: Your gross income from main business activities. For Investment Holding Companies, this includes dividends and interest income.
    • Estimated Chargeable Income: Your projected taxable profit after deducting allowable expenses, but before applying tax exemptions (like SUTE or PTE).
    • Financial Records: While audited accounts are preferred, management accounts are acceptable for estimating ECI.
    • Accounting Period: Ensure the filing corresponds to the correct Year of Assessment (YA) based on your Financial Year End (FYE).

    Who Can Submit ECI on Behalf of the Company

    The company is legally responsible for the accuracy of all ECI information submitted. ECI submissions may be made by:

    • Company Directors or authorized internal staff.
    • Tax Agents / Accounting Firms formally appointed via CorpPass.

    Note: Even when a third party submits on the company’s behalf, the company remains fully accountable for the correctness of the declared figures.

    What Happens If You Fail to File ECI?
    Failing to file ECI brings penalties
    Failing to file ECI brings penalties

    Failing to submit your Estimated Chargeable Income (ECI) within the three-month statutory window is considered non-compliance and may trigger several consequences from IRAS:

    • Estimated Notice of Assessment (NOA): IRAS may issue an automated tax bill based on historical data or industry benchmarks, which could be higher than your actual tax liability.
    • Immediate Payment Obligation: You must pay the tax stated in the Estimated NOA within one month of issuance, even if you plan to file an objection later.
    • Loss of GIRO Installments: Late filers cannot use interest-free monthly payment plans and must pay the full tax in a lump sum, which may strain cash flow.
    • Financial Penalties: IRAS may impose composition fees of up to S$5,000 for late filing. Persistent non-compliance may lead to additional enforcement measures under the Income Tax Act.

    Always file your ECI within three months of your Financial Year-End (FYE) to protect cash flow and ensure accurate tax assessment. If your company qualifies for an administrative waiver (Revenue ≤ S$5M and NIL ECI), maintain proper documentation of your self-assessment to avoid disputes with IRAS.

    Common Mistakes When Filing ECI

    Filing Estimated Chargeable Income (ECI) may seem straightforward, but companies frequently make errors that can lead to penalties, inflated tax assessments, or unnecessary administrative burdens. Avoiding these common pitfalls is essential for seamless compliance:

    • Missing the Filing Deadline: This is the most frequent error. Failing to file within three months after your Financial Year-End (FYE) triggers automated estimated assessments from IRAS and disqualifies your company from interest-free GIRO installment plans.
    • Incorrect Revenue Classification: Companies often mistakenly include non-operating income, such as capital gains from the sale of fixed assets, which should be excluded from ECI. Conversely, investment holding companies sometimes forget to include dividends and interest income as part of their revenue.
    • Misunderstanding ECI Waivers: Many small businesses continue to file ECI despite meeting both waiver criteria (Revenue <=5M and NIL ECI). While not a penalty-bearing mistake, it creates unnecessary administrative work. Always self-assess your eligibility before proceeding with a filing.
    • Inaccurate Taxable Income Estimation: Significant discrepancies between your ECI and the final figures in your Form C/C-S can raise red flags. While it is an “estimate,” it should be based on reliable management accounts to avoid potential queries from IRAS.
    • Unauthorized Portal Access: A common technical hurdle occurs when a staff member attempts to file without the proper “Corporate Tax” role assigned in Corppass. Ensure all filers—whether internal staff or third-party agents—are officially authorized to prevent rejected submissions.

    Key Tip: Before clicking ‘Submit’, double-check that your revenue figures align with your management accounts and confirm that your Year of Assessment (YA) is correct. If you are unsure about your taxable income deductions, consulting a tax professional can prevent costly amendments later.

    ECI Filing vs. Corporate Income Tax Return – What’s the Difference?

    While both ECI filing and the Corporate Income Tax Return relate to your company’s taxable income, they serve different purposes and follow distinct timelines in the Singapore tax cycle. Think of ECI as your “preliminary declaration” and the Tax Return as your “final settlement.”

    Feature ECI (Estimated Chargeable Income) Corporate Income Tax Return (Form C / C-S)
    Primary Purpose Provides an early estimate of taxable income to IRAS. Reports actual taxable income and computes final tax payable.
    Filing Deadline Within 3 months after the Financial Year-End (FYE). By 30 November of the relevant Year of Assessment (YA).
    Basis of Figures Based on estimated figures (projections from management accounts). Based on final financial statements and tax computations.
    Tax Impact Determines provisional installments (GIRO) and early payment. Determines the final tax bill and settles any balance/refund.
    Requirement Mandatory for all companies unless a waiver applies. Mandatory for all companies, even if an ECI has been filed.

    Key Takeaways:

    • Cash Flow Management: ECI filing is primarily about estimating your tax early to qualify for interest-free installments and managing your company’s cash flow.1
    • Final Compliance: The Corporate Income Tax Return (Form C/C-S) is the definitive report of your actual income. Filing an ECI does not replace the need to file your final Tax Return.
    • Accuracy: Both filings are required for full compliance. Any discrepancies between your ECI and your final Tax Return will be adjusted by IRAS in the final Notice of Assessment.

    How Koobiz Can Help with ECI Filing in Singapore

    Koobiz specializes in helping businesses file ECI accurately and on time.

    Why choose Koobiz:

    • Expertise: Years of experience in Singapore corporate tax and ECI filing.
    • Accuracy & Compliance: Avoid penalties and estimated assessments from IRAS.
    • Time-Saving: We handle the filing so your team can focus on growing the business.
    • Stress-Free: Professional guidance ensures smooth and worry-free ECI submission.

    With Koobiz, ECI filing is simple, reliable, and fully compliant, giving your business peace of mind.
  • Maximize Income Tax Relief Singapore 2026: Complete Guide to Deductions & New Rules

    Maximize Income Tax Relief Singapore 2026: Complete Guide to Deductions & New Rules

    [SUMMARIES]

    Total Relief Cap: There is a firm limit on how much total personal tax relief you can claim. For the 2026 tax year, this cap is set at S$80,000 per person.

    Course Fees Relief Cessation: The S$5,500 tax relief for course fees is no longer available for expenses you paid in 2025.

    Updated WMCR: For children born or adopted from January 1, 2024 onwards, the Working Mother’s Child Relief is now a fixed cash amount instead of a percentage of the mother’s income.

    CPF Top-Up Limits: You can get tax relief for topping up your or your loved ones’ CPF accounts, but it’s capped at S$16,000 total (S$8,000 for yourself, S$8,000 for others). Note that top-ups matched by a government grant no longer qualify.

    Donation Multiplier: The 250% tax deduction for qualifying donations to IPCs remains a powerful tool for reducing chargeable income through Dec 31, 2026.

    [/SUMMARIES]

    For the 2026 Year of Assessment (YA), maximizing income tax relief singapore means adapting to new rules. With the removal of the SG60 Rebate and Course Fees Relief, the focus shifts to core strategies like retirement contributions and family support. Koobiz presents this essential guide to help you claim every eligible deduction.

    ⚠️Critical Warning: The S$80,000 Cap

    No matter how many reliefs you qualify for, the total amount you can subtract from your income is capped at S$80,000. If you have a high income, it’s crucial to calculate your total reliefs before making extra voluntary contributions to avoid putting money where it won’t give you a tax benefit.

    Understanding Singapore Personal Income Tax 2026

    Singapore uses a progressive tax system. This means the tax rate you pay increases as your taxable income rises. Tax reliefs are simply tools to lower your “chargeable income”—the final amount the tax authority (IRAS) uses to calculate your tax bill.

    Your residency status is key. If you live in Singapore for 183 days or more in a year, you are taxed at lower resident rates. Effective tax planning starts with knowing your income level and which tax bracket you fall into. Koobiz emphasizes that strategic tax planning begins with knowing exactly where you fall on the income ladder.

    Who Needs to File Tax in 2026?

    Minimum Income & No-Filing Service (NFS
    Minimum Income & No-Filing Service (NFS

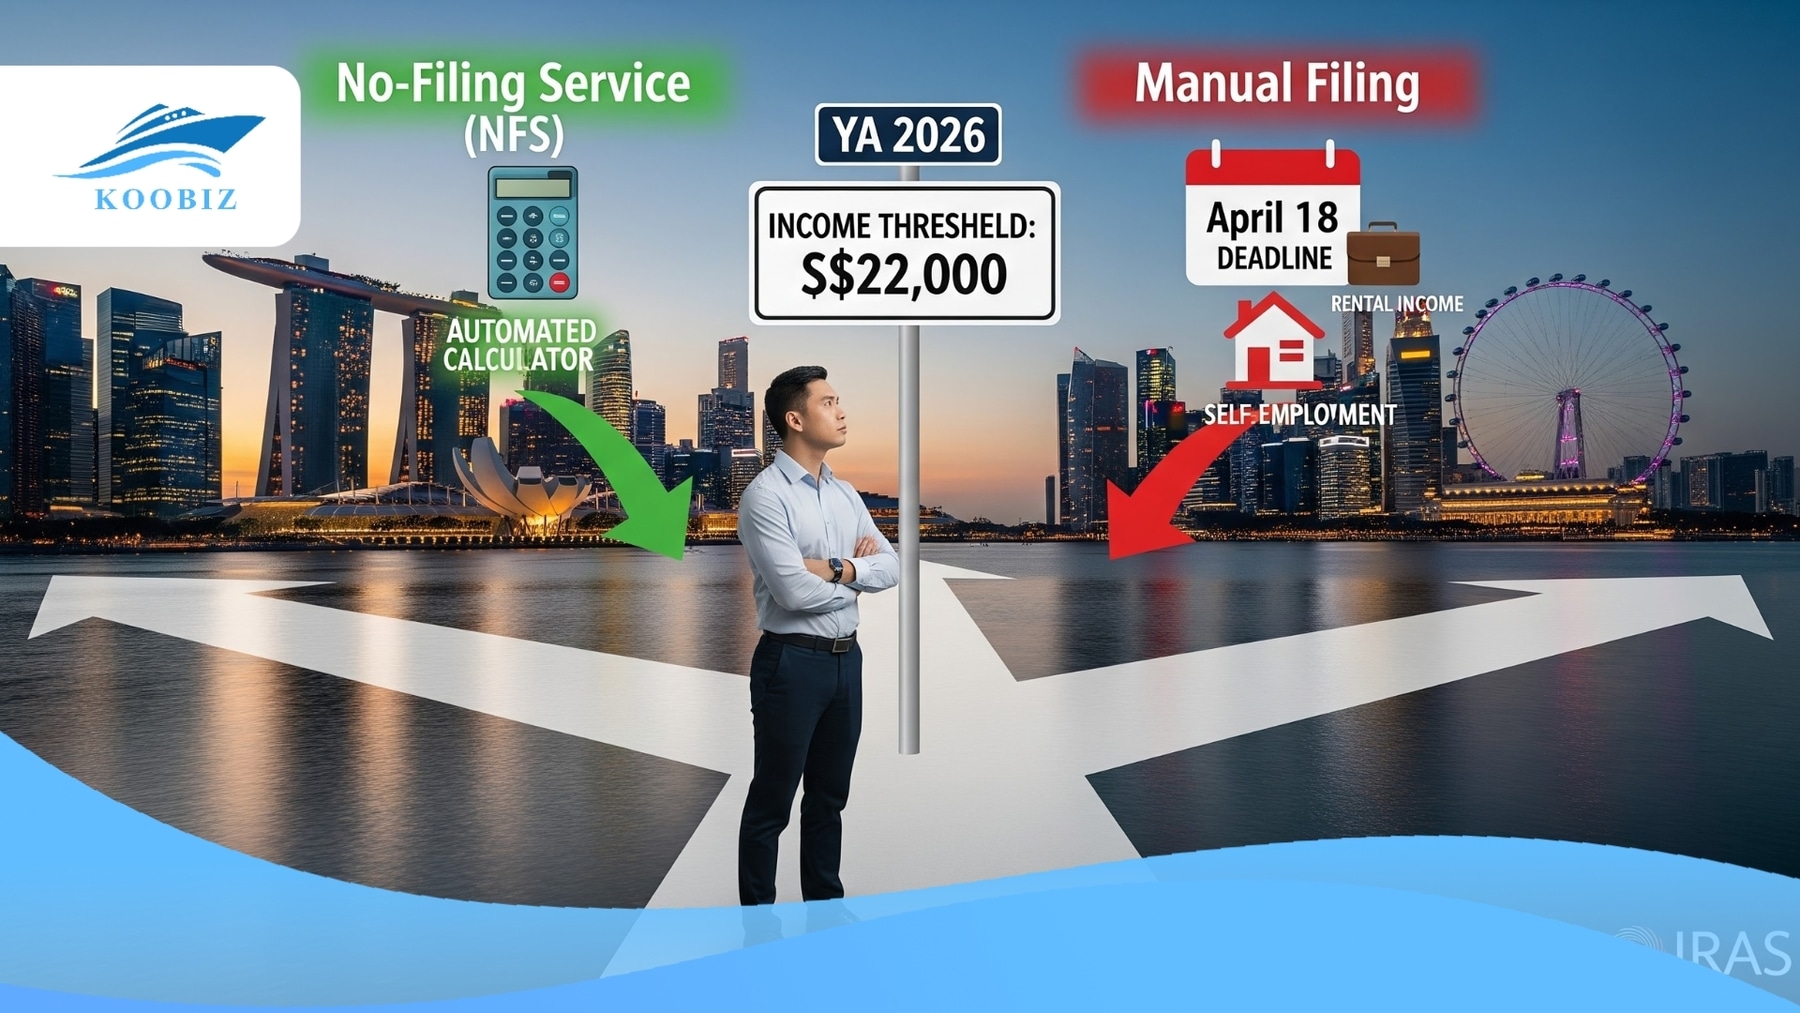
    You generally need to file a tax return if your total annual income in 2025 exceeded S$22,000. You must also file if IRAS sends you a notice, or if you need to claim certain reliefs that aren’t applied automatically. According to data from the Singapore Ministry of Finance in 2025, over 60% of taxpayers now benefit from the No-Filing Service (NFS), where their taxes are computed automatically based on data from employers and government agencies. However, individuals with rental income or self-employment earnings must still manually verify their details on the myTax Portal by the April 18 deadline.

    Resident Tax Rates for YA 2026

    The tax rates for residents remain the same. Your first S$20,000 of income is not taxed. The rates then increase step-by-step, with the highest rate applied to income over S$1,000,000.

    Chargeable Income (S$) Tax Rate (%) Gross Tax Payable (S$)
    First 20,000 0% 0
    Next 10,000 2% 200
    Next 10,000 3.5% 350
    Next 40,000 7% 2,800
    Next 40,000 11.5% 4,600
    Next 40,000 15% 6,000
    Next 40,000 18% 7,200
    Next 40,000 19% 7,600
    Next 40,000 19.5% 7,800
    Next 40,000 20% 8,000
    Next 180,000 22% 39,600
    Next 500,000 23% 115,000
    Above 1,000,000 24%

    For example, someone earning S$120,000 would typically owe about S$7,950 in tax before any reliefs. However, by maximizing income tax relief singapore strategies, that same individual could potentially drop into a lower effective tax bracket, saving thousands of dollars in final payments.

    Core Family and Individual Reliefs for YA 2026

    The main personal reliefs fall into categories like Earned Income Relief, Child Reliefs, and Parent Reliefs. These are designed to help with the costs of living and supporting dependents. For many families, these reliefs provide the biggest reduction to their taxable income. Most are applied automatically if IRAS has your updated family details.

    Working Mother’s Child Relief (WMCR) Fixed-Dollar Update

    The relief for working mothers has changed for children born or adopted from January 1, 2024. It is now a fixed amount instead of a percentage of the mother’s salary.

    Child Order Born Before 1 Jan 2024 (Old Scheme) Born On/After 1 Jan 2024 (New Scheme)
    1st Child 15% of mother’s earned income S$8,000
    2nd Child 20% of mother’s earned income S$10,000
    3rd Child + 25% of mother’s earned income S$12,000

    This transition aims to provide more equitable support to lower- and middle-income working mothers. According to the National Population and Talent Division (NPTD) report of 2024, this policy shift was designed to simplify tax planning for young families while ensuring that tax benefits are not disproportionately skewed toward high earners.

    Parent and Handicapped Parent Relief

    You can claim this relief if you support a parent, grandparent, or great-grandparent who earned less than S$8,000 in the previous year. The amount depends on whether you live together:

    • Living Together:
      • S$9,000 per parent
      • S$14,000 per handicapped parent
    • Not Living Together:
      • S$5,500 per parent
      • S$10,000 per handicapped parent

    Only one person can claim relief for a specific dependent, so siblings should agree on who will claim it, especially if one is in a higher tax bracket where the savings are greater. Koobiz advisors often suggest that siblings discuss this early to maximize the household’s total tax savings, especially if one sibling is in a higher tax bracket.

    Retirement Savings: CPF and SRS Strategies

    The primary methods for retirement-based tax reduction are the CPF Cash Top-up and the Supplementary Retirement Scheme (SRS), which together can reduce your chargeable income by up to S$51,700 for Singaporeans. To understand the best path, one must compare the immediate tax savings against the liquidity constraints of these accounts.

    Feature CPF Cash Top-Up (SA/RA) Supplementary Retirement Scheme (SRS)
    Tax Relief Cap Max S$16,000 (S$8k self + S$8k loved ones) Max S$15,300 (Citizens/PR) / S$35,700 (Foreigners)
    Interest Rate ~4.0% p.a. (Risk-free) 0.05% p.a. (Must invest to grow)
    Withdrawal Only at Retirement Age (Age 55/65 rules) Anytime (Subject to penalties if early)
    Tax on Withdrawal Tax-Exempt 50% Tax Concession (at retirement age)
    Penalty N/A (Locked in) 5% penalty + 100% tax (if withdrawn early)

    As we move into 2026, the income tax relief singapore benefits of these schemes are more critical than ever, especially with the $80,000 cap in mind. Koobiz recommends that taxpayers calculate their total family reliefs first before deciding how much to “fill” their retirement accounts to avoid exceeding the cap.
    CPF Cash Top-up Relief (S$16,000 Max)

    You can get tax relief for topping up your own or your loved ones’ CPF Retirement or Special Accounts. The total relief is capped at S$16,000 per year, split equally between yourself and others. Specifically, a major update for YA 2026 is that cash top-ups that receive a matching grant under the Matched Retirement Savings Scheme (MRSS) are no longer eligible for tax relief. This ensures that taxpayers do not “double-dip” by receiving both a government grant and a tax deduction for the same dollar. According to CPF Board statistics from 2025, over 300,000 members utilized the cash top-up scheme to boost their retirement nest egg while simultaneously lowering their tax obligations.

    Maximizing the Supplementary Retirement Scheme (SRS)

    The SRS is a voluntary scheme where every dollar you contribute gives you a dollar of tax deduction. It’s particularly useful for higher earners, as it allows you to defer tax until retirement when your income (and tax rate) may be lower. At retirement, only 50% of the money you withdraw is taxed. For a foreigner earning a high salary, maximizing SRS contributions can lead to significant immediate tax savings. Koobiz highlights that for a foreigner earning S$250,000, a full SRS contribution can result in immediate tax savings of over S$6,000. It is a vital tool in the income tax relief singapore arsenal for those looking to optimize their wealth management.

    Charitable Giving and NSman Benefits

    250% Donation Deduction & NSman Relief
    250% Donation Deduction & NSman Relief

    Donating to approved charities and having served National Service (NS) can also lower your tax bill. The government uses these reliefs to encourage charitable giving and recognize national service. To illustrate this, the 250% donation deduction remains one of the most generous tax incentives in the Singapore system.

    Pro Tip: Always check the Charity Portal before making large donations to ensure the organization is an approved Institution of a Public Character (IPC). Only donations to IPCs qualify for the 250% tax deduction.

    How the 250% Donation Deduction Works

    When you donate to an approved charity, you don’t just subtract the donation amount. You get to subtract 250% of it. So, a S$1,000 donation reduces your taxable income by S$2,500. This scheme is extended until the end of 2026. If your total reliefs hit the S$80,000 cap, the extra benefit from donations can be carried forward to use in future years. According to a Commissioner of Charities report in late 2025, individual donations saw a 12% increase year-on-year, largely driven by taxpayers seeking to offset higher income brackets while supporting local causes.

    NSman Relief for Self, Wife, and Parents

    NSman relief is a unique aspect of income tax relief singapore, providing a token of appreciation for those who have served or support those who serve in the Singapore Armed Forces, Police Force, or Civil Defence. The amounts are:

    • NSman (Self): S$1,500 – S$5,000 (depending on rank & active service status)
    • Wife of NSman: S$750
    • Parent of NSman: S$750

    While the individual amounts are small, they are often automatically credited and provide a steady, reliable reduction in tax for the majority of male Singaporean citizens.

    Important Changes: What You Can No Longer Claim

    The main difference for YA 2026 is the removal of broad-based education reliefs and one-off rebates. Koobiz advises reviewing your tax liability early, as the absence of these credits may result in a higher final bill than expected.

    Benefit YA 2025 (Previous) YA 2026 (Current) Action Required
    Course Fees Relief Claim up to S$5,500 ❌ REMOVED Check for employer training grants or SkillsFuture usage.
    SG60 Tax Rebate 60% Off (Max S$200) ❌ REMOVED Budget for full tax payment; no automatic discount this year.

    Note: The shift in policy moves away from personal tax deductions toward direct subsidies like SkillsFuture and the Enterprise Innovation Scheme.

    Niche Caregiver and Household Reliefs

    Grandparent Caregiver Relief & FDWL Relief Removal
    Grandparent Caregiver Relief & FDWL Relief Removal

    There are specialized reliefs for caregivers and households, though options have narrowed with the removal of the Foreign Domestic Worker Levy (FDWL) Relief. The Grandparent Caregiver Relief remains the primary benefit for working mothers relying on family support.

    Grandparent Caregiver Relief (GCR)

    Grandparent Caregiver Relief allows a working mother to claim S$3,000 if her parent, grandparent, or in-law is looking after her children. Use this checklist to confirm your eligibility:

    GCR Eligibility Checklist:

    • Claimant: Must be a Working Mother (fathers are not eligible).
    • Caregiver: Your parent, grandparent, or parent-in-law (including from spouse’s side).
    • Caregiver Status: Must not be engaged in any trade, business, or employment.
    • Child: Singapore Citizen, aged 12 or below in 2025 (or unmarried/handicapped children).

    Koobiz Note: This relief is “stackable.” A mother of two with a retired mother-in-law providing care can claim this S$3,000 on top of her WMCR and other child reliefs.

    Foreign Domestic Worker Levy (FDWL) Relief Removal

    It is important to remember that the Foreign Domestic Worker Levy (FDWL) Relief was completely removed starting from YA 2025. Specifically, this means for your YA 2026 filing, you can no longer claim a tax deduction for the levies paid for your helper. The government replaced this broad tax relief with more targeted subsidies, such as the Home Caregiving Grant, which provides direct cash assistance to families caring for those with permanent disabilities or frailty. According to the Ministry of Social and Family Development (MSF), this shift ensures that financial support reaches those with the highest caregiving needs, regardless of their income tax bracket.

    Strategic Planning: The S$80,000 Personal Relief Cap

    Tax Strategy: The S$80,000 Personal Relief Cap
    Tax Strategy: The S$80,000 Personal Relief Cap

    The S$80,000 cap is a hard limit on all your personal reliefs combined. If your Earned Income Relief, Child Relief, Parent Relief, CPF, and SRS add up to more than S$80,000, you will only get S$80,000 of benefit. This rule ensures higher earners still pay a fair share of tax.

    A common mistake is making large voluntary CPF or SRS contributions late in the year without realizing you’ve already reached the cap through other reliefs. This results in locking away money without getting the expected tax reduction.

    Case Study: The “Maxed Out” Taxpayer

    Consider a high-earning working mother in 2026 with three children (all born before 2024) and two elderly parents living with her. We assume she has an Annual Earned Income of S$120,000.

    Her reliefs would be calculated as follows:

    • Earned Income Relief: S$1,000
    • WMCR (Percentage based):
      • 1st Child (15% of S$120k): **S$18,000**
      • 2nd Child (20% of S$120k): **S$24,000**
      • 3rd Child (25% of S$120k): **S$30,000**
      • WMCR Subtotal: S$72,000
    • Parent Relief: S$9,000 x 2 (living with her) = **S$18,000**

    Total Relief Calculation:

    S$1,000 + S$72,000 + S$18,000 = **S$91,000**

    In this scenario, she has already exceeded the S$80,000 cap (S$91,000 > S$80,000) before even considering her mandatory CPF contributions or SRS. Specifically, any additional cash top-ups to her CPF or SRS accounts would provide zero tax relief for YA 2026. Koobiz suggests that such individuals should focus on other wealth management strategies, such as tax-efficient investments or corporate structuring, rather than seeking further personal tax reliefs.

    About Koobiz Services

    Navigating the complexities of income tax relief singapore and broader financial regulations requires a partner who understands the local landscape. Koobiz (koobiz.com) is a premier professional services firm specializing in:

    • Company Formation: Seamless incorporation services for entrepreneurs looking to establish a presence in Singapore’s vibrant economy.
    • Banking Account Advisory: Expert guidance on opening corporate and personal bank accounts with leading financial institutions in Singapore.
    • Tax, Accounting, and Audit: Comprehensive compliance services, from GST filing and corporate tax optimization to statutory audits.

    Whether you are an individual taxpayer looking to optimize your personal tax bill for YA 2026 or a business owner seeking to leverage the Enterprise Innovation Scheme, Koobiz provides the expertise needed to navigate Singapore’s regulatory environment with confidence. Visit koobiz.com today to learn how we can support your financial growth.

  • File GST Return Singapore: Essential Form F5 Guide & Input Tax Claims for Businesses

    File GST Return Singapore: Essential Form F5 Guide & Input Tax Claims for Businesses

    [SUMMARIES]

    Mandatory Electronic Filing: All GST returns (Form F5) must be filed electronically via the IRAS myTax Portal, typically on a quarterly basis.

    Net GST Calculation: Your payment or refund depends on the difference between Output Tax (collected from customers) and Input Tax (paid on business purchases).

    Strict Deadlines: Filings are due one month after the end of your prescribed accounting period; late filings incur an immediate $200 penalty plus $200 per outstanding month.

    Claiming Input Tax: Valid tax invoices addressed to your company are required; expenses must be business-related and not explicitly disallowed (e.g., private car usage).

    Error Correction: Errors with a Net GST difference of ≤ S$3,000 can be adjusted in the next return; larger errors require a Form F7.

    2026 Updates: Form F5 now includes boxes for Reverse Charge on Low-Value Goods and Remote Services.

    [/SUMMARIES]

    Managing tax compliance is a priority for every Singapore business for any registered company, and knowing how to accurately file your Singapore GST return is essential. For both new startups and established SMEs, understanding the nuances of Form F5 and maximizing your Input Tax Claims can significantly impact your cash flow and compliance standing. At Koobiz, we understand that tax season can be stressful, which is why we have compiled this comprehensive guide. This article will walk you through the essential steps of filing, clarify the definition of output versus input tax, and explore the crucial conditions for claiming refunds, ensuring your business remains compliant with IRAS regulations while optimizing its tax position.

    Disclaimer: Information is accurate as of January 2026. Please verify the latest updates on the IRAS website.

    What is the Singapore GST Return (Form F5)?

    Form F5 and GST tax for Singapore businesses
    Form F5 and GST tax for Singapore businesses

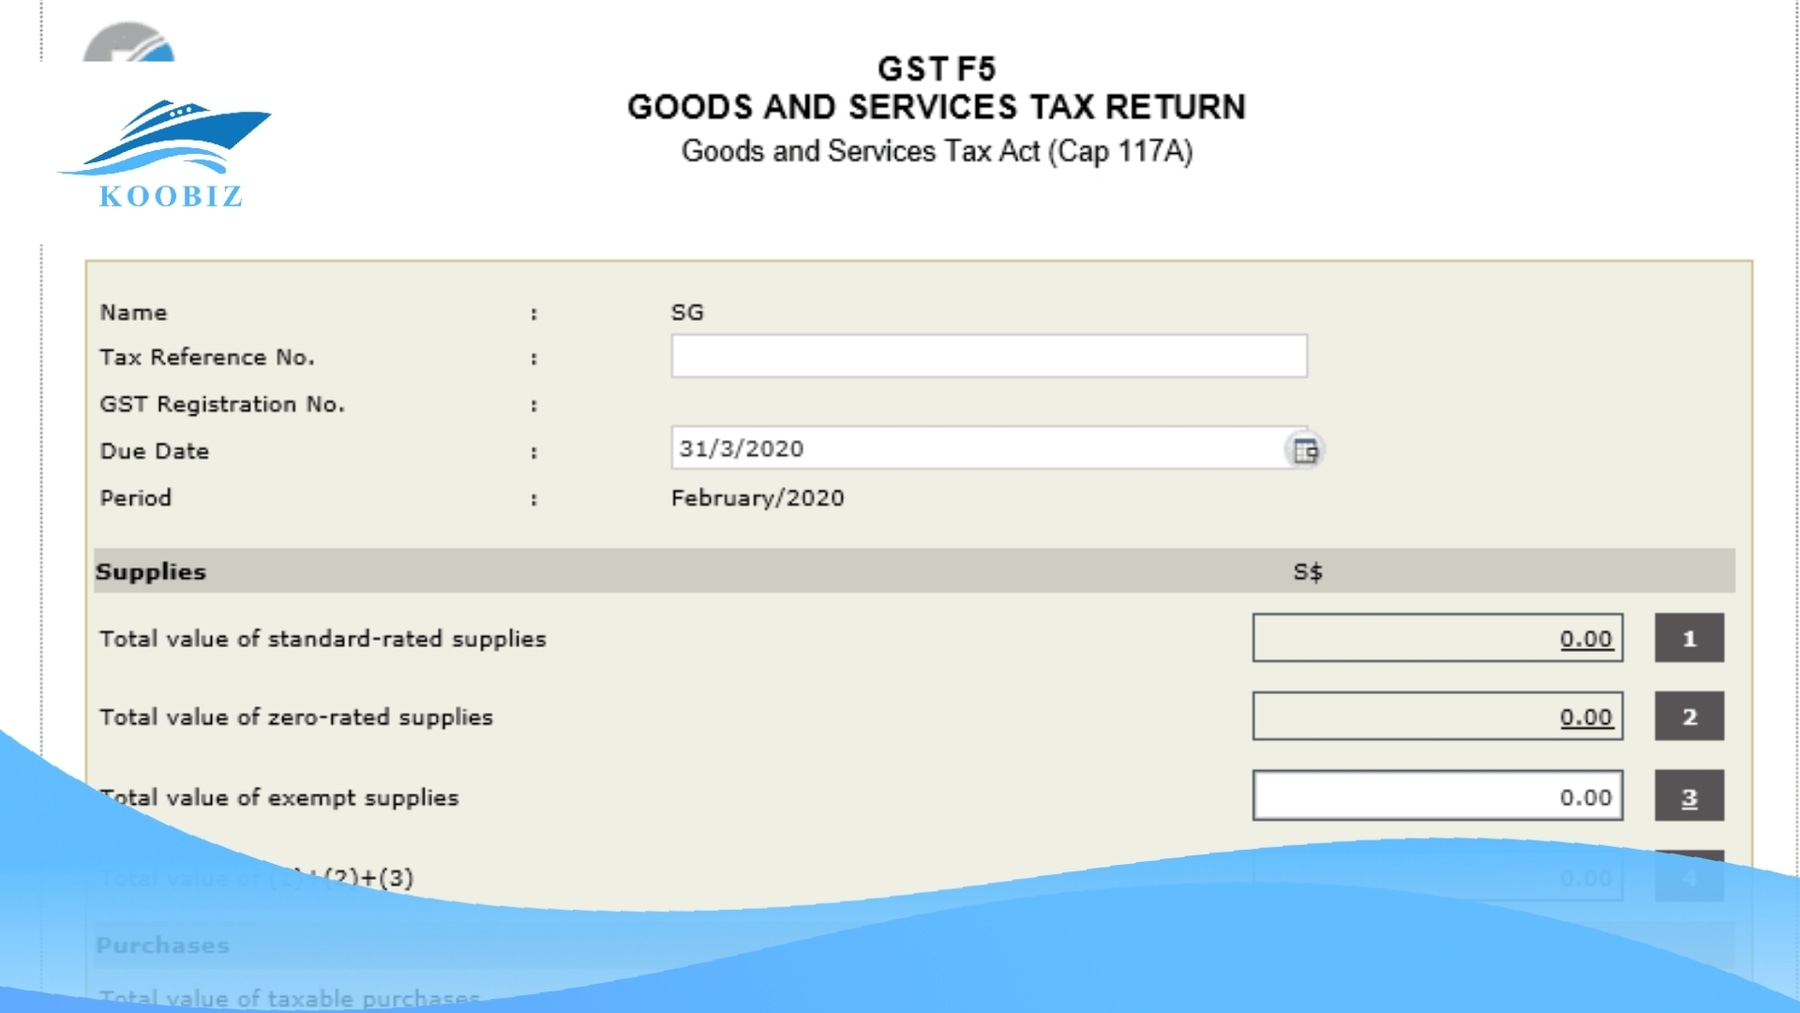
    The Singapore GST Return, officially known as Form F5, is the mandatory electronic filing used by GST-registered businesses to report their GST transactions to the Inland Revenue Authority of Singapore (IRAS). Below are the key features of Form F5 that every GST-registered business should understand:

    • Electronic Filing: Form F5 must be submitted electronically through the IRAS myTax Portal; paper submissions are not accepted.
    • Summary Declaration: The return consolidates GST collected from customers (output tax) and GST paid to suppliers (input tax) for the relevant accounting period.
    • Net Calculation: Based on the figures reported, Form F5 determines whether the business must pay GST to IRAS or is entitled to a GST refund.
    • Periodic Filing: Unlike corporate income tax, GST returns are filed on a recurring basis, most commonly on a quarterly schedule.
    • Authentication: Submission of Form F5 requires Singpass access with the appropriate Preparer or Approver role assigned.

    For businesses, this document is the “source of truth” regarding their indirect tax liability. Accuracy in Form F5 is essential, as incorrect or inconsistent filings may trigger IRAS reviews, audits, or penalties.

    Who Must File a GST Return in Singapore?

    In Singapore, businesses required to file a GST return generally fall into two categories: those compulsorily registered for GST and those voluntarily registered with IRAS. If your business belongs to either category, the filing of Form F5 is mandatory and required by law, regardless of whether the business records a profit or a loss for the period.

    Detailed breakdown of these categories includes:

    1. Compulsory Registrants: These are businesses whose taxable turnover exceeds S$1 million at the end of the calendar year (Retrospective View) or is expected to exceed S$1 million in the next 12 months (Prospective View). Once GST registration is effective, the business is required to file Form F5 for each assigned accounting period without exception.
    2. Voluntary Registrants: These are businesses that elect to register for GST, often to recover input tax incurred on significant startup or operating costs, despite having annual turnover below S$1 million. Once approved by IRAS, they are bound by the same filing rules as compulsory registrants and usually must remain registered for at least two years.

    When is the GST Return Deadline?

    The GST return deadlines in Singapore
    The GST return deadlines in Singapore

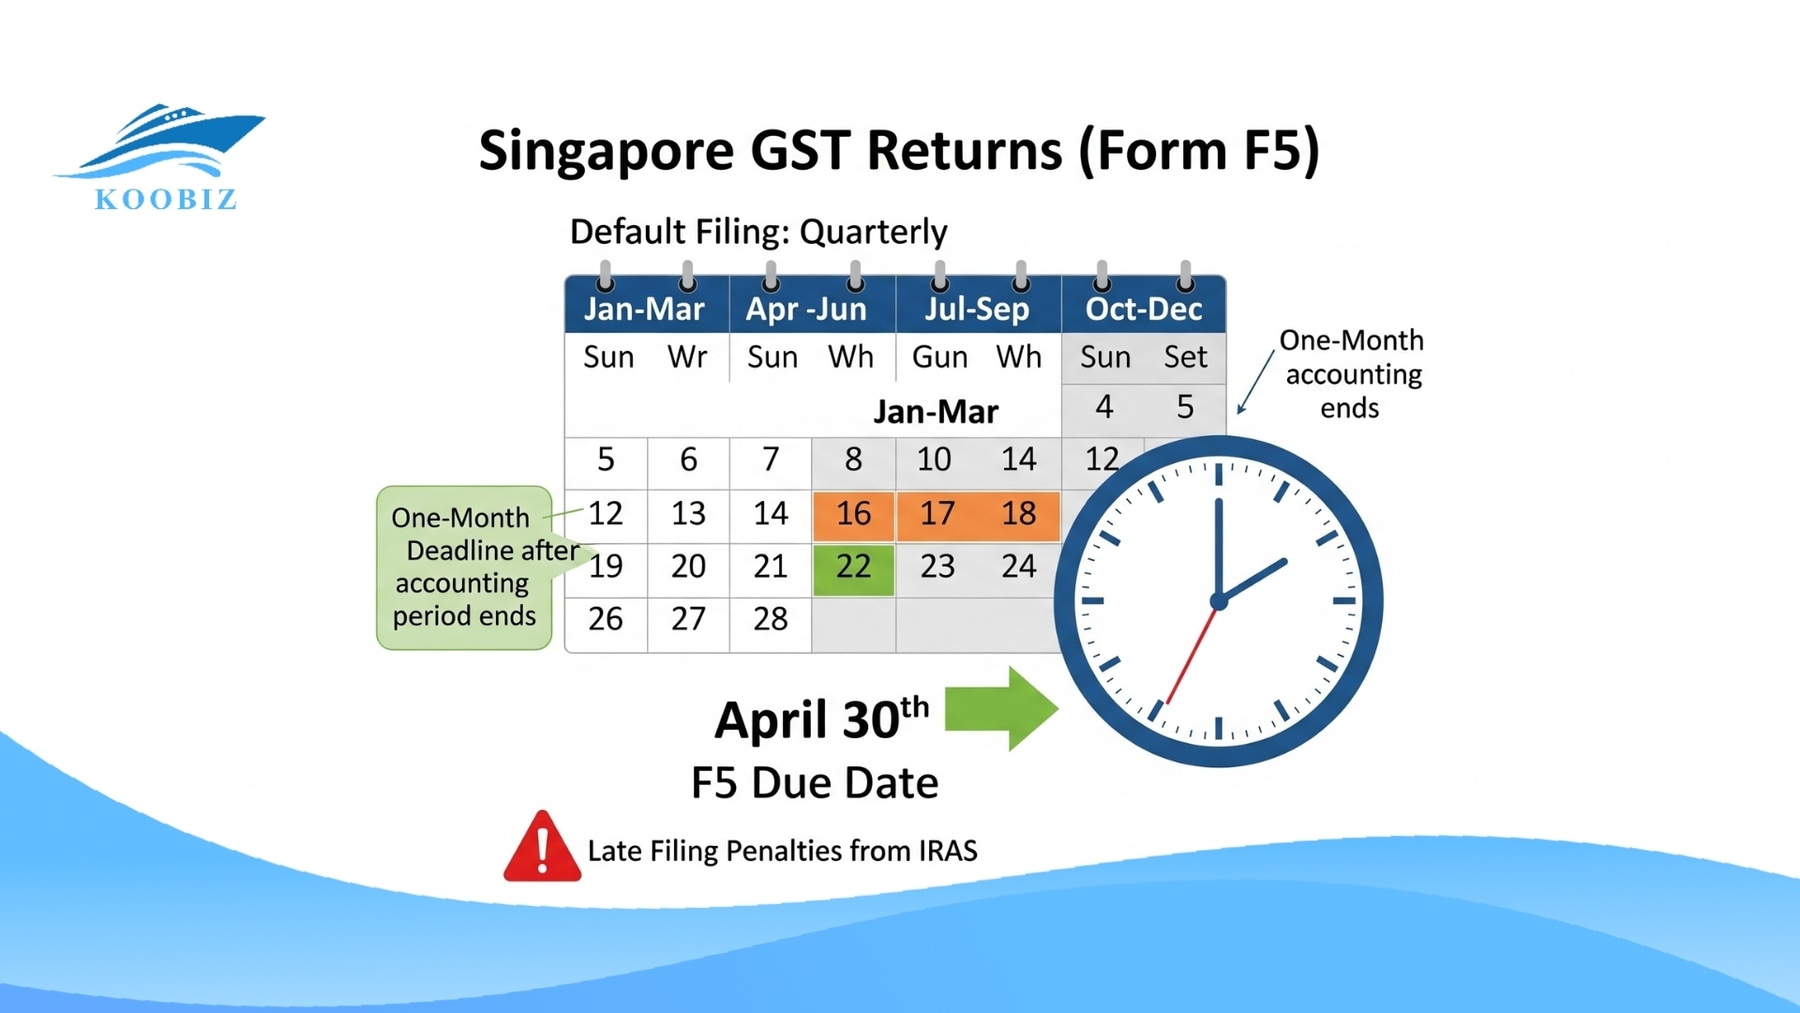
    GST returns in Singapore are subject to strict statutory deadlines and must generally be filed within one month after the end of the prescribed accounting period. For most GST-registered businesses, the standard filing frequency is quarterly, although some businesses may opt for or be assigned a monthly filing cycle by IRAS.

    Here is how the timeline works structurally:

    • Quarterly Filing: This is the default frequency. If your accounting period covers January to March, your Form F5 and the corresponding payment are due by April 30th.
    • Monthly Filing: This filing frequency typically applies to exporters or businesses that regularly receive GST refunds to support cash flow. If the accounting period is January, the Form F5 deadline falls at the end of February.
    • GIRO Deadlines: Although the GST filing deadline remains the end of the following month, businesses enrolled in GIRO enjoy a later payment deduction date, usually on the 15th of the month following the filing deadline, which provides a modest cash flow benefit.

    Failure to meet these dates triggers immediate compliance actions from IRAS. Accordingly, it is essential for businesses to closely monitor their assigned accounting period end dates to ensure timely GST compliance.

    How to File GST Return in Singapore: Step-by-Step Guide

    How to File GST Return in Singapore
    How to File GST Return in Singapore

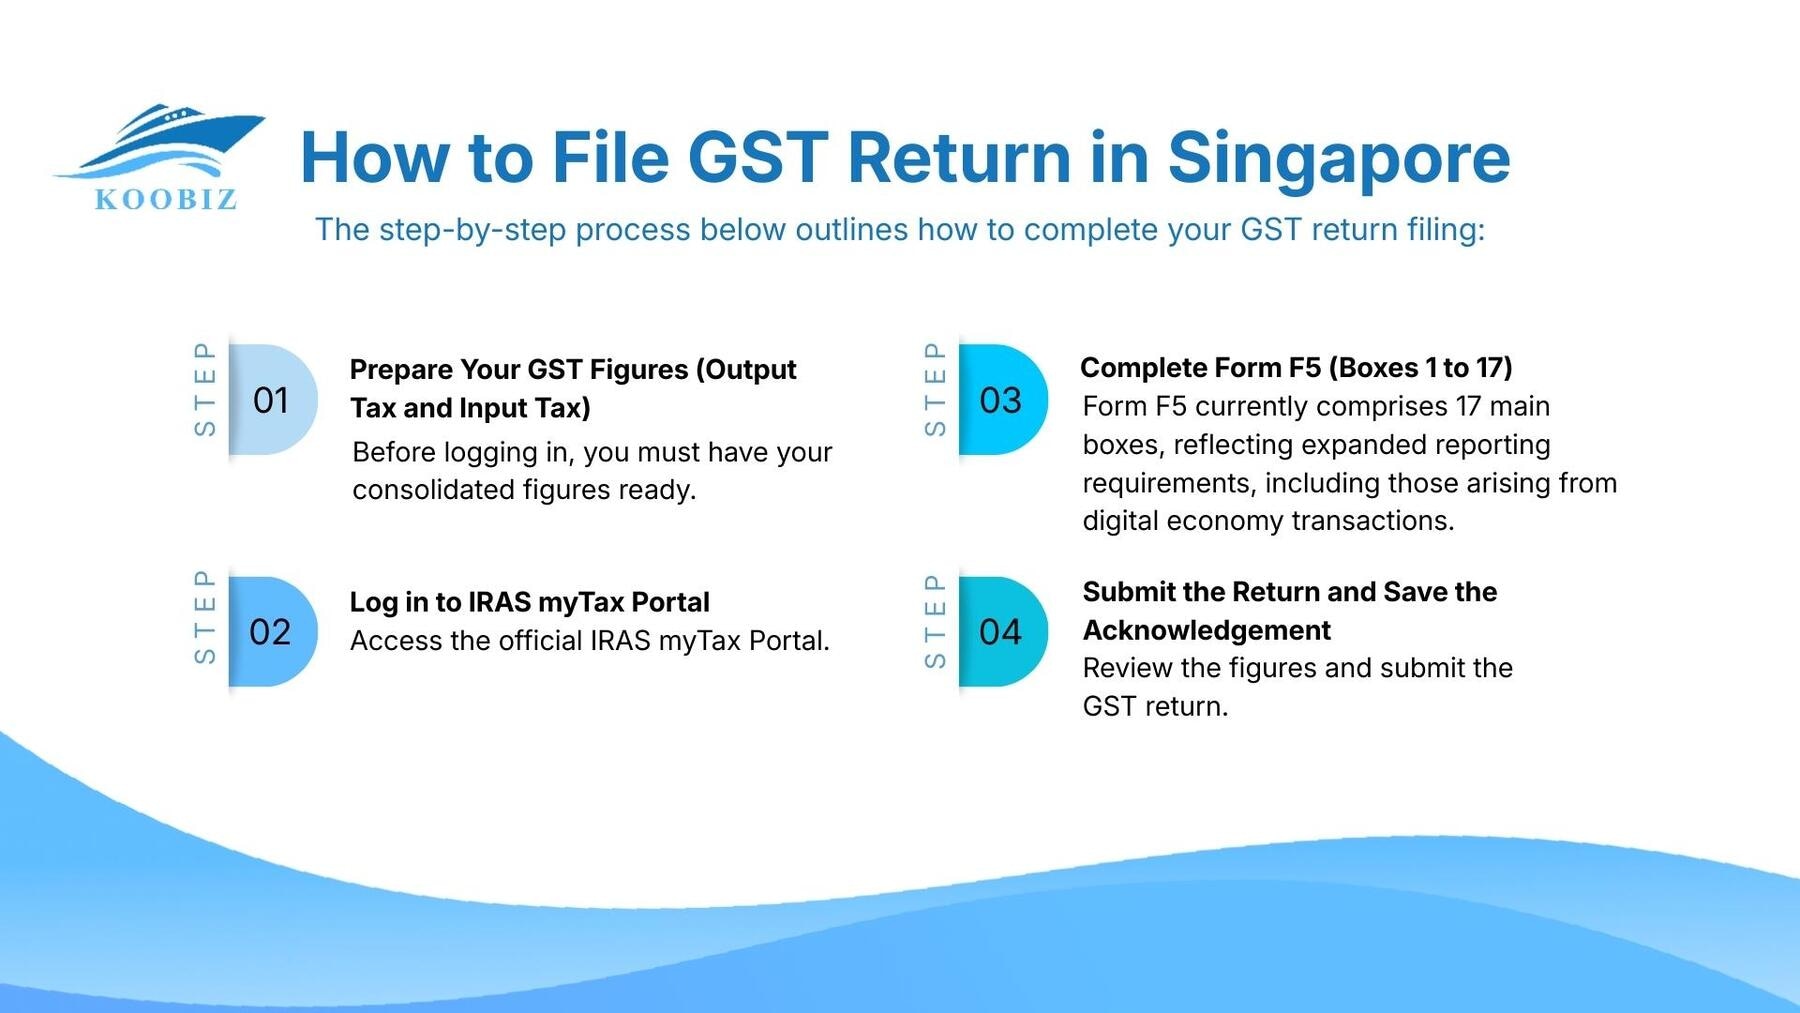
    Filing a GST return in Singapore follows a standardized digital process on the IRAS myTax Portal and requires Singpass authentication together with accurate data entry. The process is designed to allow businesses to meet their GST compliance obligations efficiently, provided that their accounting records are properly maintained. The step-by-step process below outlines how to complete your GST return filing:

    Step 1: Prepare Your GST Figures (Output Tax and Input Tax)

    Before logging in, you must have your consolidated figures ready. The difference between what you collect and what you pay determines your liability.

    • Output Tax: This refers to the 9% GST charged on taxable supplies made to customers. This GST is collected on behalf of IRAS and does not form part of business income.
    • Input Tax: This is the GST paid on business-related purchases such as rent, utilities, and inventory, which may be claimed to offset output tax, subject to IRAS rules.

    Ensuring these figures are backed by valid tax invoices and proper listing is the foundation of a correct return. In practice, many businesses reconcile these figures before logging into the portal to avoid delays or session timeouts during submission.

    Step 2: Log in to IRAS myTax Portal

    • Access the official IRAS myTax Portal.
    • Log in using your Singpass (ensure you are authorized as an “Approver” or “Preparer” in CorpPass).
    • From the main menu, select “GST” and then choose “File GST Return / Edit Past Return.”
    • The system will display the relevant Form F5 for the current filing period.

    Step 3: Complete Form F5 (Boxes 1 to 17)

    Form F5 currently comprises 17 main boxes, reflecting expanded reporting requirements, including those arising from digital economy transactions. Accurate completion of these boxes is a key compliance requirement.The table below summarises the purpose of each box and the information to be reported.

    Box No. Description What to Enter
    1 Total Value of Standard-rated Supplies Value of standard-rated supplies subject to 9% GST, including applicable reverse charge supplies.
    2 Total Value of Zero-rated Supplies Value of exported goods and international services (0%).
    3 Total Value of Exempt Supplies Value of financial services, residential property sales/rentals.
    4 Total Value of Supplies Automatically calculated (Sum of Boxes 1, 2, and 3).
    5 Total Value of Taxable Purchases Value of taxable purchases supported by valid tax invoices, including purchases subject to reverse charge.
    6 Output Tax Due GST collected on sales + GST accounted for under Reverse Charge.
    7 Input Tax and Refunds Claimed Input tax claimed, including GST paid to suppliers and GST claimable under reverse charge, subject to IRAS conditions.
    8 Net GST to be Paid/Claimed Automatically calculated (Box 6 – Box 7).
    9-12 Special Scheme/Refunds Boxes relating to special GST schemes and refunds, such as the Major Exporter Scheme (MES) and Tourist Refund Scheme, where applicable.
    13 Revenue from Remote Services For Overseas Vendors: Value of digital services supplied.
    14 Imported Services & Low-Value Goods Reverse Charge: Declare value of imported services and low-value goods (LVG) subject to RC.
    15-17 Electronic Marketplace Marketplace Operators: Declaration for supplying/redelivering low-value goods.

    Note: Boxes 18-21 may appear for businesses approved under the Import GST Deferment Scheme (IGDS).

    Step 4: Submit the Return and Save the Acknowledgement

    • Review all entered figures against your source documents.
    • Submit the GST return once all figures have been reviewed and confirmed.

    Important: Once verified and submitted, proceed to the acknowledgement page. Koobiz advises saving a PDF copy of this acknowledgement immediately for your audit trail.

    What are the Conditions for Claiming Input Tax?

    Conditions and disallowed input tax expenses
    Conditions and disallowed input tax expenses

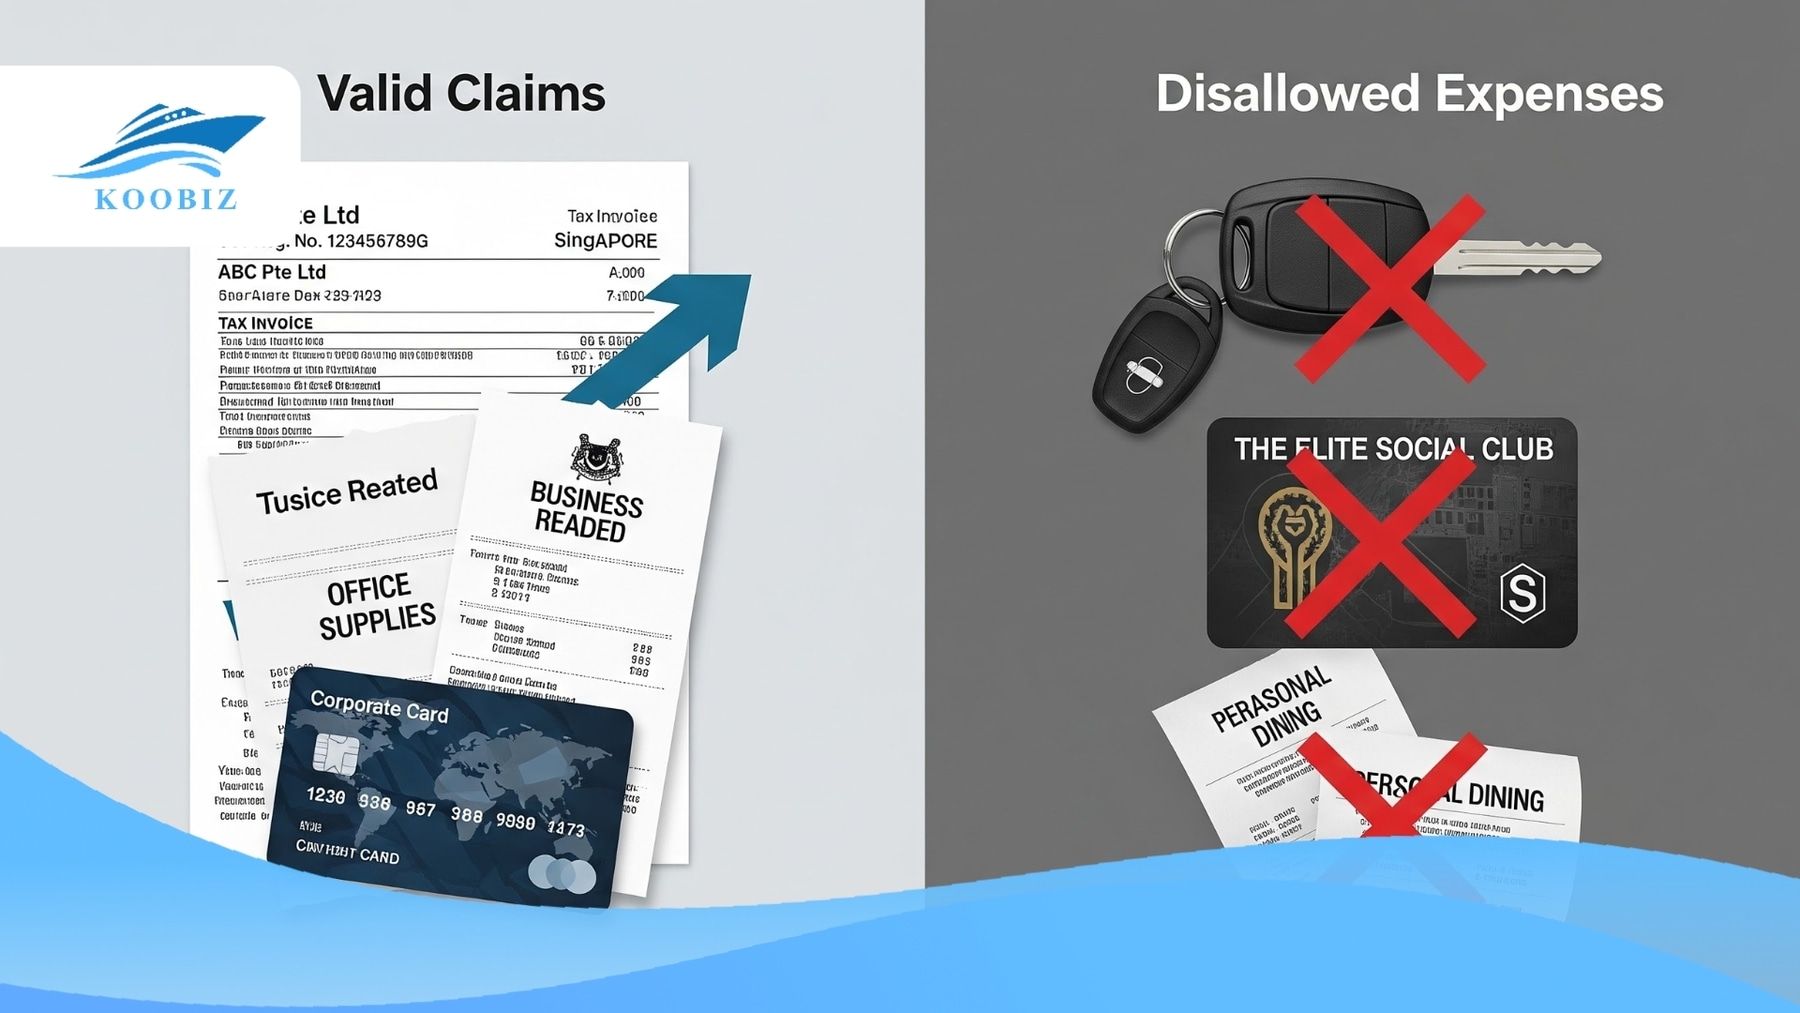
    Input tax may be claimed, provided that the expenses are incurred strictly for business purposes and are supported by valid tax invoices issued to the company. The input tax credit mechanism prevents the cascading of GST; however, IRAS applies strict conditions on which expenses qualify for input tax claims.

    To be eligible for an input tax claim, all of the following conditions must be met:

    1. You must be GST-registered at the time the tax was incurred.
    2. The goods or services must have been supplied directly to the GST-registered business and not to a third party.
    3. The goods or services are used for the purpose of your business.
    4. The business must hold a valid tax invoice or simplified tax invoice at the time the input tax is claimed.

    Common Disallowed Input Tax Expenses

    Certain categories of expenses are specifically blocked from input tax claims under GST regulations. Even where such expenses are incurred for business-related purposes, GST claims are disallowed to prevent misuse.

    • Private Passenger Cars: GST incurred on the purchase, repair, or rental of private cars (S-plated) is disallowed, even if used for client meetings.
    • Medical and Accident Insurance: Expenses relating to medical and accident insurance for staff are generally disallowed, unless the insurance is compulsory under WICA or a collective agreement.
    • Club Subscription Fees: Entrance and subscription fees to recreation clubs are blocked.
    • Family Benefits: Benefits provided to the family members of employees are not eligible for input tax claims.

    Can You Claim Input Tax Without a Tax Invoice?

    A valid tax invoice is mandatory evidence required under GST legislation to support any input tax claim. A receipt or a credit card slip is often insufficient if it does not contain the supplier’s GST registration number, the tax amount, and the breakdown of the supply.

    For amounts not exceeding S$1,000, a simplified tax invoice is acceptable. For amounts exceeding S$1,000, a full tax invoice stating the company’s name and address is required. If an original tax invoice is lost, a certified true copy must be obtained from the supplier before the input tax is claimed in Form F5.

    How to Calculate Net GST Payable or Refundable in Singapore?

    Net GST is calculated by subtracting total input tax claimed (Box 7) from total output tax due (Box 6). This calculation determines whether GST is payable to IRAS or refundable to the business.

    • Net GST Payable: If Box 6 > Box 7, you owe IRAS the difference. Any GST payable must be settled by the filing deadline using approved payment methods such as GIRO, PayNow Corporate, or AXS.
    • Net GST Refundable: If Box 7 > Box 6, IRAS owes you money. This situation commonly arises for exporters who make zero-rated supplies but incur GST on local purchases. Refunds are usually credited directly into your bank account, provided you have no other outstanding tax liabilities.

    With the standard filing process covered, it is crucial to understand that not all business models fit the generic mold. GST reporting may become more complex as businesses expand or engage in cross-border transactions.

    Special GST Schemes and Complex Filing Scenarios

    Special GST schemes, such as the Major Exporter Scheme (MES) and the Reverse Charge mechanism, modify standard GST reporting to support cash flow management and maintain tax neutrality.

    How to File Under the Major Exporter Scheme (MES) in Singapore?

    The Major Exporter Scheme (MES) suspends the payment of GST at the point of importation to improve cash flow.

    • Do not claim input tax on such imports, as GST was not paid at the point of importation.
    • Declare the value of imported goods under MES in Box 9 of Form F5.This confirms the goods have entered the GST chain without immediate tax payment.

    What is the Reverse Charge Mechanism in Singapore?

    The reverse charge mechanism applies to imported services and low-value goods (LVG) to ensure tax parity between local and overseas suppliers.This applies to businesses not entitled to full input tax credit (e.g., banks, developers, charities) or those exceeding import thresholds.

    • Scope: Imported services and imported low-value goods (not exceeding S$400 per item and delivered via air or post).
    • Filing: The business accounts for GST as both supplier and customer by reporting the value of the supply in Box 1 and Box 14 of Form F5, while claiming the corresponding input tax in Box 7, subject to eligibility.

    Handling Pre-registration Input Tax Claims in Singapore

    Newly GST-registered businesses may recover GST incurred on pre-registration setup costs, subject to specific consumption and eligibility rules imposed by IRAS.

    • Goods: Claimable only if the goods are held by the business at the effective date of GST registration. Goods acquired more than six months before registration must not have been consumed or supplied prior to the effective registration date.
    • Services: Claimable if incurred up to 6 months prior to registration (e.g., rental, legal fees).

    In practice, businesses are required to prepare a pre-registration GST checklist and supporting apportionment calculations to substantiate such claims.

    Managing GST Errors and Compliance Issues in Singapore

    GST compliance requires distinguishing between minor administrative errors that may be adjusted in a subsequent return and material errors that require formal disclosure to IRAS.

    Form F5 vs. Form F7: How to Correct Mistakes in Your Return

    Form F7 is the prescribed mechanism for correcting errors in a previously filed GST return, effectively amending the original Form F5.

    • Administrative Concession (Revised): Under the administrative concession, errors may be adjusted in the next GST return only if the net GST difference does not exceed S$3,000, regardless of the total value of supplies. The 5% rule applies only to non-GST errors.
    • Mandatory F7: Any error exceeding the S$3,000 net GST threshold must be corrected immediately via Form F7.
    • Tip: The GST F7 Calculator available on the IRAS website may be used to assess eligibility for the administrative concession.

    What Happens If You File Late? (Penalties & Composition Fines)

    Late GST compliance results in a cumulative penalty regime that escalates over time.

    • Late Submission Fee: An immediate S$200 penalty is imposed once the deadline passes. An additional S$200 is added for every completed month the return remains outstanding, capped at S$10,000.
    • Late Payment Penalty: A 5% penalty is imposed immediately on unpaid GST. If the tax remains unpaid after 60 days, an additional 2% penalty is charged for each completed month, capped at 50% of the unpaid tax.

    How to File a Nil GST Return in Singapore

    Even where no GST transactions occurred, a nil return must still be filed to avoid late filing penalties.

    1. Log in to myTax Portal.
    2. Select the ‘Nil Return’ option.
    3. Declare zero supplies and zero claims, then submit the return.

    Managing Singapore’s GST obligations requires careful compliance with statutory rules and filing requirements.From determining your filing liability to maximizing your input tax claims and avoiding the pitfalls of late submission, every step in the File GST Return Singapore process impacts your business’s bottom line.

    Koobiz specializes in simplifying these corporate complexities for you. Whether you need assistance with company incorporation in Singapore, opening a corporate bank account, or managing your ongoing tax, accounting, and audit obligations, our team of experts is ready to assist. We ensure that your GST returns are filed accurately and on time, allowing you to focus on growing your business.

    Visit us at koobiz.com to learn more about how we can support your business journey in Singapore.

  • Find Your IRAS DIN Number (Document ID) for Corporate Tax Filing

    Find Your IRAS DIN Number (Document ID) for Corporate Tax Filing

    [SUMMARIES]

    Definition: The DIN is a unique reference number tied to a specific tax return type and Year of Assessment (YA), used to identify outstanding returns.

    Retrieval: You can view it via the myTax Portal (using Corppass) or on the Notice to File letter, if your company still receives paper mail.

    Crucial Distinction: Never use the DIN for making payments; use the Payment Reference Number (usually your UEN) to avoid transaction errors.

    Access: Corporate tax e-filing is based on Corppass authorization, not the DIN. You usually do not need to enter the DIN to access the filing wizard manually.

    Dormant Companies: Companies granted a waiver of Income Tax Return submission do not require a DIN, as they are not required to file Form C-S/C for that YA.

    [/SUMMARIES]

    Having trouble locating your IRAS DIN number during tax season? This is a common issue for many companies. At Koobiz, we often help clients who hit a roadblock because they cannot find their Document Identification Number (DIN) or confuse it with other tax references. This guide addresses that issue clearly and directly. We will show you exactly what the DIN is, how to quickly find it on the myTax Portal, and why you must distinguish it from your Payment Reference Number to ensure a seamless filing for Form C-S/C.

    What is the Document Identification Number (DIN) issued by IRAS?

    DIN IRAS: unique tax identification code
    DIN IRAS: unique tax identification code

    The Document Identification Number (DIN) is a unique alphanumeric code issued by the Inland Revenue Authority of Singapore (IRAS) to identify a particular tax return document for a specific Year of Assessment (YA).

    The DIN functions as a reference key that links a company to its tax filing obligation for a specific Year of Assessment. Its core characteristics include:

    • Dynamic & Unique: Unlike your company’s Unique Entity Number (UEN), which never changes, a new DIN is generated for every specific tax form and financial year.
    • Identifier (Not Password): Since e-filing became mandatory in 2020, the DIN is no longer used as a portal access credential. However, it remains the unique identifier for the specific return in the IRAS backend system.
    • Error Prevention: It acts as a coordinate in the IRAS database, ensuring your submission lands in the correct assessment period (e.g., preventing a YA 2026 filing from overwriting YA 2025 data).

    Therefore, while you may not always be required to enter the DIN to initiate e-filing, possessing the correct DIN (or knowing where to find it) is essential for verifying your filing status and communicating with IRAS.

    How to Find Your DIN for Corporate Tax Filing: A Step-by-Step Guide

    There are two primary methods to retrieve your DIN: accessing it digitally through the myTax Portal or locating it physically on the hard-copy Notice to File sent by IRAS.

    Using the correct retrieval method helps ensure that you reference the valid DIN for the relevant Year of Assessment.

    Find IRAS DIN on myTax Portal Notice
    Find IRAS DIN on myTax Portal Notice

    Viewing DIN via the myTax Portal (Digital Method)

    As part of Singapore’s digital tax administration framework, the digital retrieval method is the most reliable and immediate way to find your DIN, especially if physical mail has been misplaced.

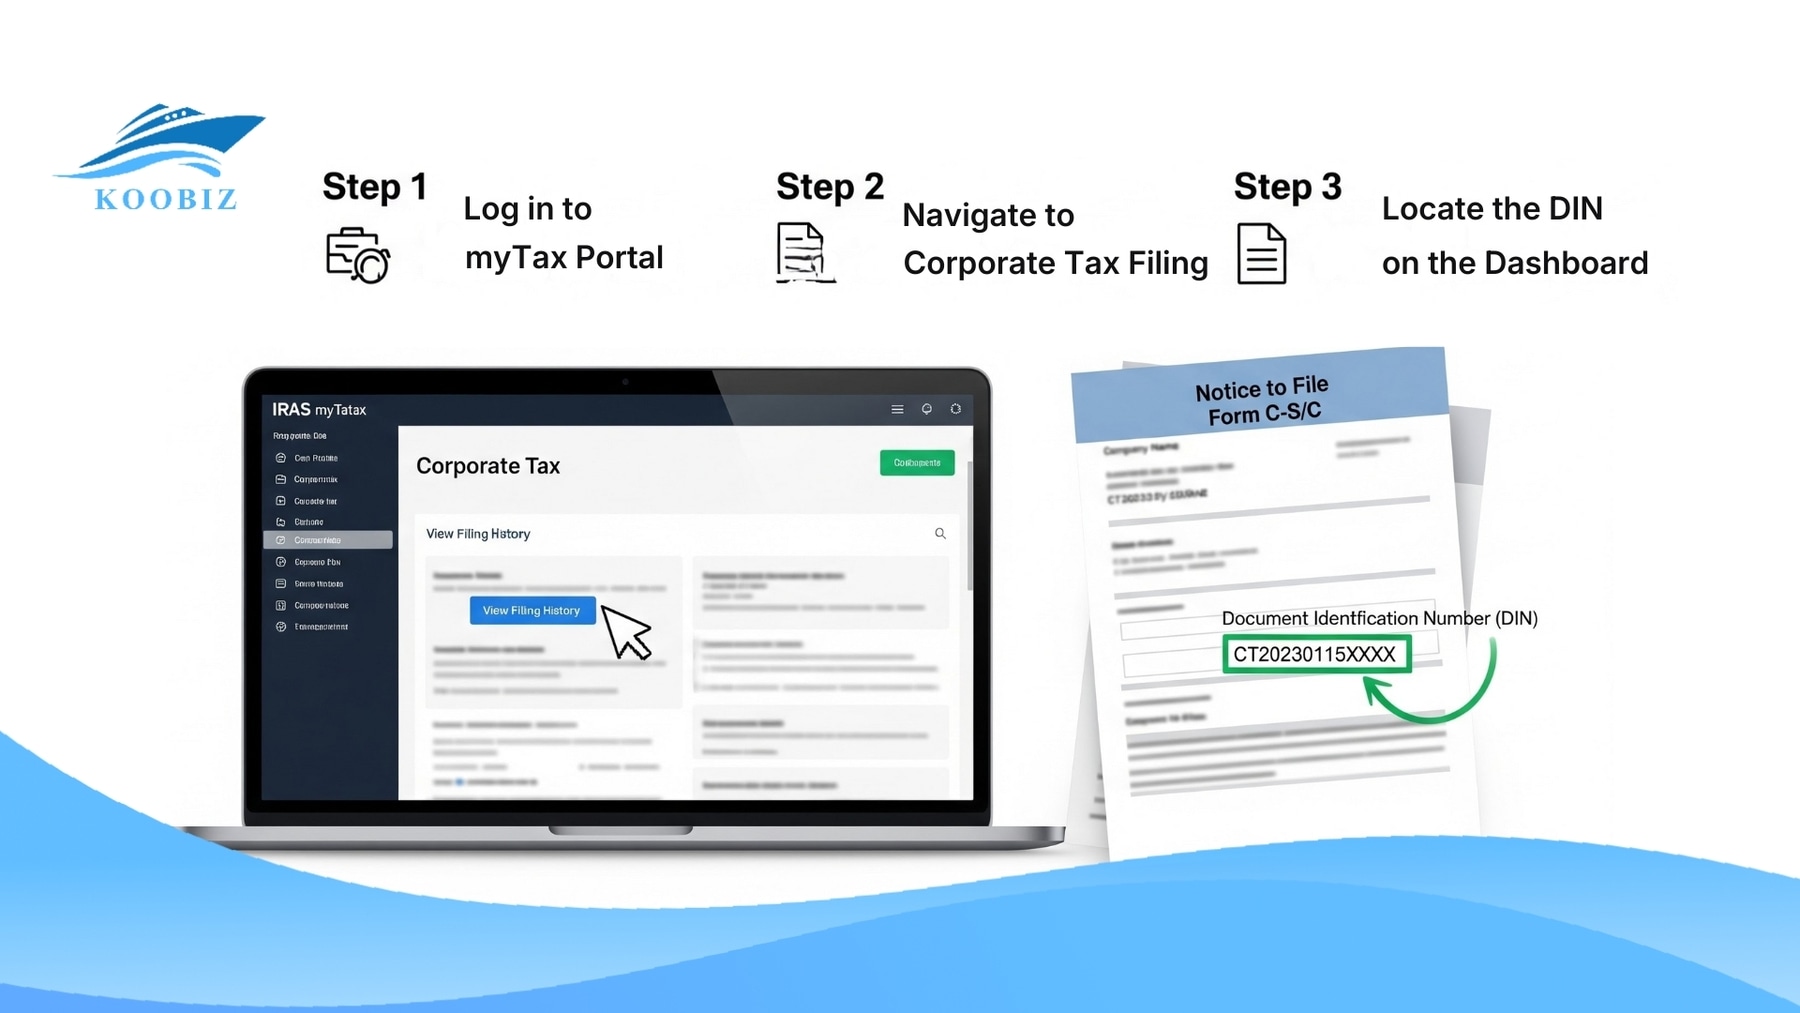
    1. Log in to myTax PortalNavigate to the official IRAS myTax Portal. You must select “Business” and log in using your Corppass. Ensure that the user logging in has been authorized for “IRAS (Corporate Tax)” digital services within the Corppass system. Without this specific authorization, the relevant menus will not appear.
    2. Navigate to Corporate Tax FilingOnce logged in, look for the menu bar at the top. Hover over “Corporate Tax” and select “File Form C-S/C”. This is the specific section where the filing process begins.
    3. Locate the DIN on the DashboardUpon entering the filing section, the system will display a list of outstanding tax returns for various Years of Assessment. Look for the row corresponding to the current YA (e.g., YA 2026). The Document Identification Number (DIN) will be clearly displayed in that row.

    Note: In most cases, you can click the “File” button to launch the wizard without manually typing this number.

    It is important to note that if the status shows “Filed” or “Processed,” the DIN may still be visible for reference, but the action required has already been completed.

    Locating the DIN on Physical Tax Notices (Paper Notice to File)

    IRAS has largely transitioned to digital correspondence, and most tax notices are now issued electronically. However, if your company still receives paper mail, the hard-copy Notice to File remains the authoritative reference.

    When IRAS sends out the filing notification (usually between January and May, depending on the company’s financial year-end), it arrives as a formal letter titled “Notice to File Form C-S/C”.

    Where to look:

    1. Check the top-right corner: On the very first page of the letter, locate the box containing key details.
    2. Verify the Year: Ensure the Year of Assessment matches the tax year you intend to file for.
    3. Identify the DIN: Look for the Document ID (DIN) printed in bold text. It is typically a long string of numbers (e.g., 20268888888).

    This physical document is valuable for record-keeping. At Koobiz, we advise clients to scan this document immediately upon receipt and save it in their cloud storage, ensuring the DIN is accessible to their accountant or tax agent even if the physical paper is misplaced later.

    Difference Between DIN and Payment Reference Number

    The DIN is used to identify specific tax returns, while the Payment Reference Number is the only reference that should be used for tax payments.

    Distinguishing between these two numbers is important, as using the wrong reference is a common cause of “payment not received” errors in Singapore’s corporate tax system.

    Feature Document Identification Number (DIN) Payment Reference Number
    Primary Purpose Identification: Used to identify a specific tax return document, such as Form C-S for YA 2026. Payment: Identifies the payer and allocates funds to the correct tax account.
    When to Use Reference only. Displayed on the filing dashboard and used when referring to or requesting copies of filed returns. Used for GIRO, PayNow, AXS, or Internet Banking transfers.
    Structure Dynamic: A new DIN is issued for each Year of Assessment (YA) and for each specific tax form. Static: Usually your company’s Unique Entity Number (UEN), which remains constant across years.
    IRAS Destination Returns Processing Branch. Collections Branch.

    Important Warning: If you attempt to enter the DIN into your bank’s “Bill Reference” field when paying tax, the transaction will likely fail, or worse, the payment may be held in a suspense account by IRAS because the banking system does not recognize the DIN format as a valid payment account. IRAS places the responsibility on taxpayers to ensure the correct Payment Reference Number is used for all payments.

    Troubleshooting Common Issues with IRAS DIN Retrieval

    Troubleshooting Common Issues with IRAS DIN Retrieval
    Troubleshooting Common Issues with IRAS DIN Retrieval

    In practice, locating a DIN may not always be straightforward, especially for back-dated filings or when access to the myTax Portal is restricted.

    Resolving these issues requires an understanding of how IRAS archives past records and controls Corppass user access.

    Can You Retrieve a DIN for Previous Years of Assessment?

    Yes, DINs for previous Years of Assessment can still be retrieved, but the retrieval method depends on whether the return is outstanding or already processed.

    If a filing deadline for a previous YA (for example, YA 2024) was missed, the return is classified as “Outstanding. When you log into the myTax Portal and navigate to “File Form C-S/ C”, the system will usually display all outstanding returns, including those from prior years. The DIN for that specific past year will be listed there.

    If you need a DIN for a Year of Assessment that has already been filed, purely for record-keeping or verification purposes, you may need to navigate to the “View Correspondence/Notices” section of the portal. Here, you can download digital copies of past “Notices to File,” which will show the DIN as it appeared on the original digital Notice to File.

    What Should You Do If You Cannot Access myTax Portal?

    If you cannot log in to retrieve your DIN, the issue usually lies with Corppass authorization, not the IRAS system itself.

    1. Check Corppass Account: Confirm that your Corppass account is active and has not been suspended.
    2. Verify Assigned e-Services: The company’s Corppass Administrator (usually the business owner or Company Secretary) must assign the “IRAS (Corporate Tax)” e-Service to your user ID.
    3. Browser Compatibility: Sometimes, simply clearing the cache or switching to a private/incognito window resolves display issues where the dashboard fails to load.

    If these steps fail, you can contact IRAS directly via their helpline. IRAS will conduct strict identity verification before releasing any DIN-related information over the phone, in line with security protocols.

    Do Dormant Companies Need a DIN for Tax Filing?

    No. Dormant companies that have been granted a Waiver of Income Tax Return Submission generally do not receive a DIN, as they are not required to file an income tax return for that Year of Assessment.

    This exemption is commonly used when business operations are temporarily suspended, and Koobiz regularly assists clients in applying for this waiver.

    Waiver of Income Tax Return Submission

    A dormant company is one that has no revenue or income for the entire financial period. However, being dormant does not automatically exempt you from filing. A formal application for a Waiver of Income Tax Return Submission must be made to IRAS.

    Once IRAS approves this waiver:

    • IRAS will stop issuing the “Notice to File” (Form C-S/C) for the approved waiver period.
    • As a result, no DIN is generated for that Year of Assessment.
    • You do not need to log in and file anything.

    If you have not applied for the waiver, IRAS will still treat you as an active filer, issue a Notice to File, generate a DIN, and expect a submission (even if it is a “Nil” return). Accordingly, if you cannot locate a DIN, the first step is to check whether an active waiver is in place. If you don’t have a waiver and didn’t receive a DIN, you might be non-compliant and should contact a professional immediately.

    Authorising Third-Party Agents to Use Your DIN

    Authorising a third-party agent involves formally delegating access to the myTax Portal so the agent can manage filings associated with your company’s DIN.

    This is standard practice for most SMEs in Singapore that engage licensed corporate service providers such as Koobiz.

    Setting up Corppass for Tax Agents

    You do not need to give your personal Singpass or the company’s DIN directly to your accountant. Instead, authorization should be granted securely through the Corppass system.

    1. Identify the Agent: You will need the Tax Agent’s UEN (Unique Entity Number).
    2. Authorize in Corppass: The company’s Corppass Admin logs in and selects “Authorize Third Party Entity.”
    3. Select Services: Check the box for “IRAS (Corporate Tax) – Filing and Applications.”

    Once this digital handshake is complete, the Tax Agent can log in using their own credentials. They will see your company in their client list and will have access to your DIN and filing dashboard automatically. This is the most secure method of handling your corporate tax data, as it maintains a clear digital audit trail of who performed the filing.

    Navigating the nuances of IRAS compliance, from retrieving a simple DIN number to filing complex tax computations, is crucial for the longevity of your Singapore business. A missing DIN is often just a symptom of a larger administrative hurdle.

    At Koobiz, we specialize in smoothing out these operational wrinkles. Whether you need assistance with Singapore company incorporation, opening a corporate bank account, or managing your annual tax and accounting obligations, our team ensures ongoing compliance while minimizing administrative burden.

    Visit Koobiz.com today to learn more about our comprehensive corporate services.

  • How to File Form IR21: The 2026 Guide to Tax Clearance for Foreigners in Singapore

    How to File Form IR21: The 2026 Guide to Tax Clearance for Foreigners in Singapore

    [SUMMARIES]

    Mandatory Filing: Employers must file Form IR21 at least one month before a non-citizen employee ceases work or leaves Singapore.

    100% Withholding: It is a legal requirement to withhold all final monies (salary, bonus, etc.) until IRAS issues a clearance directive.

    E-Filing Speed: Utilizing the myTax Portal reduces processing time to approximately 7 working days compared to 21 days for paper forms.

    Heavy Penalties: Non-compliance can result in fines up to S$5,000 and the employer becoming liable for the employee’s unpaid taxes.

    Special Rules: The “Deemed Exercise” rule applies to ESOPs, and specific exemptions exist for ONE Pass and short-term workers.

    [/SUMMARIES]

    The process of tax clearance for foreign employees is a critical compliance pillar for any business operating in the Lion City. The process sits at the crossroads of employment law, immigration, and taxation, where even minor missteps can trigger serious consequences from the Inland Revenue Authority of Singapore (IRAS). This guide provides employers and HR teams with a clear, practical roadmap to managing Form IR21, ensuring smooth staff departures while protecting the company’s legal standing.

    Mastering tax clearance for foreign workers goes far beyond completing a form. Employers must coordinate the withholding of final payments, assess equity compensation under the “Deemed Exercise” rules, and apply the correct exemptions where applicable. This 2026 guide breaks down the latest procedures, timelines, and strategic considerations you need to achieve full regulatory compliance and avoid costly enforcement actions.

    What is Tax Clearance (Form IR21) in Singapore?

    Tax clearance for foreigners is the mandatory process requiring employers to file Form IR21 to ensure non-citizen employees settle all income tax liabilities before ceasing employment or leaving Singapore. In practice, this means the employer must submit Form IR21 to declare the employee’s final remuneration and temporarily withhold all final payments.

    This duty rests entirely with the employer. With that framework in mind, it is essential to understand the precise obligations and timelines that shape the 2026 compliance landscape. For an employee’s perspective on this process, you can also share our foreign employee’s guide to tax clearance and withheld salary.

    Legal Obligations for Employers in 2026

    In 2026, the digital-first approach of the Singapore government has made tax clearance filings almost exclusively electronic via the myTax Portal. According to the Income Tax Act, an employer must notify IRAS whenever a non-Singapore Citizen employee (including Permanent Residents and all work pass holders) ceases employment, is posted overseas for more than three months, or plans to leave the country for a period exceeding three months.

    Electronic IR21 form and Singapore financial district
    Electronic IR21 form and Singapore financial district

    Although system integration between the myTax Portal and payroll software has streamlined the workflow, the employer remains the primary accountable party. If a foreign employee departs without settling their taxes and the employer failed to submit Form IR21, the company becomes financially liable for the outstanding tax amount.

    Key Deadlines and the “One-Month Rule”

    IR21 Filing Deadline: The One-Month Rule
    IR21 Filing Deadline: The One-Month Rule

    The “One-Month Rule” is the most critical timeline. The employer must file Form IR21 at least one month before the employee’s expected date of cessation or departure.

    • Standard Case: If an employee’s last day is October 31st, the IR21 should be filed by September 30th.
    • Immediate Resignation: If a month’s notice is impossible, file the form as soon as practicable. You must provide a valid reason for the late notification in Section D of the form.
    • Impact of Delay: Late filings delay the release of an employee’s final paycheck, which can lead to labor disputes and administrative friction with the Ministry of Manpower (MOM).

    Who is Required to Undergo Tax Clearance?

    There are three main categories of individuals required to undergo tax clearance protocols: Employment Pass (EP) holders, S Pass holders, and Permanent Residents (SPR) leaving Singapore permanently. These categories are determined by both the individual’s residency status and the nature of their exit from Singapore’s tax system.

    In essence, any non-citizen whose economic ties to Singapore are ending or materially changing is brought into the tax clearance net to ensure that all income earned locally is fully accounted for before departure.

    Scenarios Requiring IR21 Filing
    Scenarios Requiring IR21 Filing

    Scenarios Requiring IR21 Filing

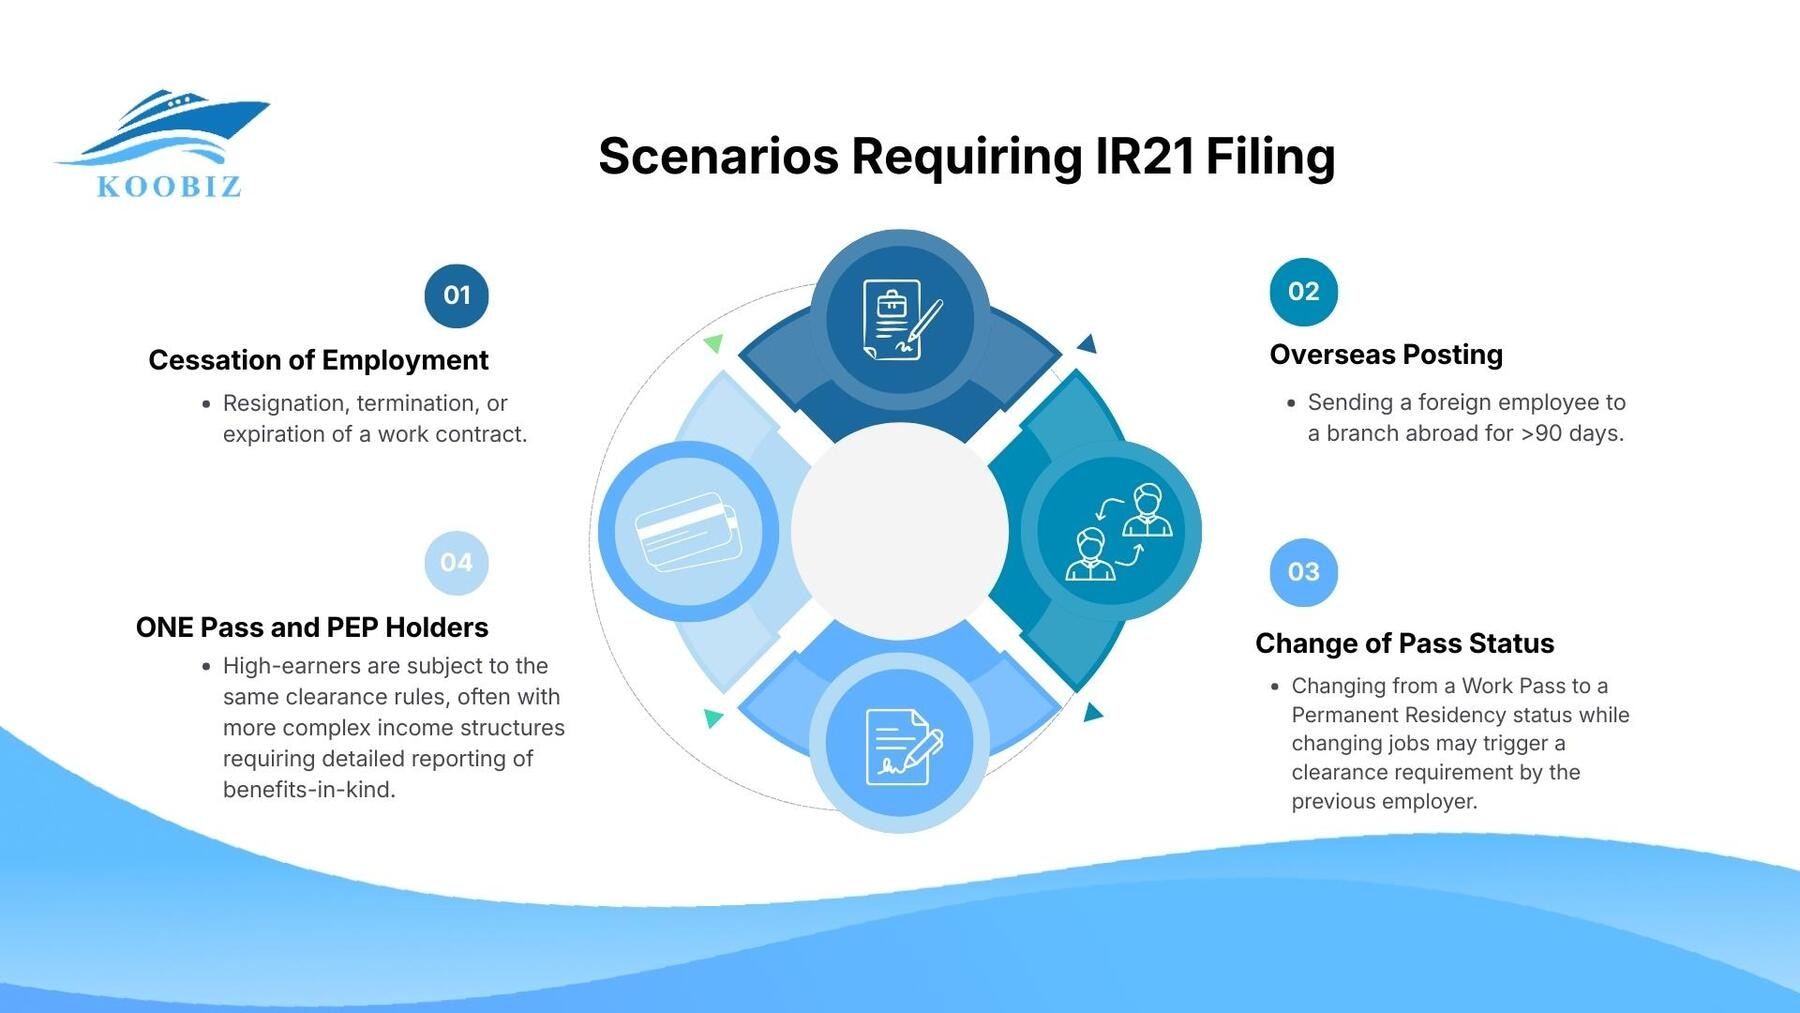
    The need for tax clearance for foreign staff is triggered by specific events:

    • Cessation of Employment: Resignation, termination, or expiration of a work contract.
    • Overseas Posting: Sending a foreign employee to a branch abroad for >90 days.
    • Change of Pass Status: Changing from a Work Pass to a Permanent Residency status while changing jobs may trigger a clearance requirement by the previous employer.
    • ONE Pass and PEP Holders: High-earners are subject to the same clearance rules, often with more complex income structures requiring detailed reporting of benefits-in-kind.
    Common Exemptions and the “60-Day Rule”

    Not every foreigner leaving a job needs tax clearance processing. IRAS provides administrative concessions to reduce the burden:

    1. The 60-Day Rule: The employee worked for 60 days or less in a calendar year (excludes directors and public entertainers).
    2. The Income Threshold: The foreigner earned less than S$21,000 annually and is not a director.
    3. The SPR Rule: The employee is a Singapore Permanent Resident who is not leaving Singapore permanently (requires a Letter of Undertaking).
    Category IR21 Required? Key Condition
    EP Holder Resigning Yes Must withhold all monies until cleared
    Short-term Consultant (<60 days) No Tax-exempt income for most roles
    SPR staying in SG No (with LOU) Must remain in Singapore job market
    ONE Pass Holder Yes Subject to complex asset reporting

    The Step-by-Step IR21 Filing Process

    The tax clearance method involves a sequence of 3 major steps resulting in a “Notification to Release Monies” or a “Directive to Pay Tax.”

    Step 1: Calculating and Withholding Final Monies

    Employers must withhold 100% of all monies due to the employee from the moment notice is given. This includes:

    • Final month’s salary and pro-rated pay.
    • Accrued bonuses, commissions, and allowances.
    • Payment in lieu of notice.
    • Gains from ESOPs/ESOWs (Employee Share Options/Ownership).

    Failure to withhold these funds is a violation of the Income Tax Act. Employers must keep these funds in the company’s account until IRAS issues a directive. To understand exactly how these tax liabilities are determined, read our guide on calculating Singapore income tax for resident vs non-resident foreigners.

    Step 2: E-filing via myTax Portal (7-Day Turnaround)

    In 2026, e-filing is the mandatory standard for efficiency.

    • E-filing: Processed within 7 working days.
    • Paper Filing: Can take up to 21 days, prolonging the period the employee’s funds are frozen.

    Step 3: Navigating Clearance Directives

    Once processed, you will receive one of two documents:

    1. Directive to Pay Tax: Specifies the amount of withheld money to be sent directly to IRAS.
    2. Notification to Release Monies: Confirms the employee has no tax liability, allowing the employer to pay the balance to the employee.

    Understanding the “Deemed Exercise” Rule for ESOPs

    Deemed Exercise Rule for ESOPs
    Deemed Exercise Rule for ESOPs

    When dealing with equity-based compensation, tax clearance protocols become significantly more complex due to the “Deemed Exercise” rule.

    How Unvested Shares are Taxed

    This rule applies to unexercised ESOPs or unvested ESOW shares held at the time of cessation. IRAS “deems” these shares to have been exercised or vested on the date of departure.

    Example: If an executive has 10,000 unvested shares, IRAS calculates the tax based on the open market value at the time of the IR21 filing. This creates a “phantom tax” where the tax is due even if the shares cannot yet be sold.

    Reassessment of Deemed Gains

    If the actual gain (when the shares eventually vest or are sold) is lower than the “deemed” gain used during tax clearance, the individual can apply to IRAS for a tax refund. This application must be made within four years of the year of assessment.
    Taxable vs. Non-Taxable Income

    During the tax clearance process, employers often struggle with what to report. The following table clarifies common income types in 2026:

    Income Type Taxable? Reporting Requirement
    Basic Salary & Bonus Yes Full amount in Form IR21
    Housing Allowance Yes Report as Benefit-in-Kind
    Airfare for Home Leave No Exempt if within specific limits
    Severance Pay Partial Subject to “retrenchment” criteria
    Unvested ESOPs Yes Subject to Deemed Exercise Rule

    Special Scenarios in 2026 Tax Clearance

    In the evolving 2026 job market, tax clearance for foreign workers often falls into “gray areas” like remote work or corporate restructuring. These are grouping categories based on the specific legal status of the company or the individual’s residency intent.

    Furthermore, these scenarios often require specialized forms beyond the standard IR21 to ensure that the employer is not unnecessarily withholding salary for an employee who isn’t actually leaving.

    Tax Clearance for SPRs: The Letter of Undertaking (LOU)

    For Singapore Permanent Residents (SPR), the tax clearance process can sometimes be bypassed. If an SPR is leaving their current job but has no intention of leaving Singapore, the employer can avoid withholding salary by having the employee sign a Letter of Undertaking (LOU).

    The employer must also confirm that the SPR does not plan to leave Singapore for a period exceeding three months. This LOU serves as a formal assurance that the individual will stay within Singapore’s tax jurisdiction, allowing income to be reported through the normal Auto-Inclusion Scheme (AIS) at year-end rather than triggering immediate tax clearance. In effect, it preserves continuity and avoids unnecessary disruption to the employee’s cash flow.

    Company Mergers and the Waiver of Tax Clearance

    Another uncommon but significant situation arises during company mergers, acquisitions, or restructurings. When a business is sold and employees are transferred to a new legal entity (NewCo), this is technically treated as a cessation of employment with the original employer.

    However, IRAS often grants a Waiver of Tax Clearance in these instances, provided that the NewCo takes over all tax liabilities and the employees’ terms of employment remain substantially the same. This prevents a mass IR21 filing event that would freeze the salaries of the entire workforce during a sensitive transition.

    Remote Work Clarifications for Global Nomads

    By 2026, many foreigners work “remotely” during their notice period. For tax clearance purposes, if an employee leaves Singapore to work from their home country during their one-month notice period, they are considered to have “ceased employment in Singapore” the moment they physically depart.

    In practical terms, this means the employer must file Form IR21 and withhold all final payments based on the employee’s actual departure date, not the contractual last working day stated in the employment agreement. The tax obligation is triggered by physical exit from Singapore, not by HR timelines.

    Research published by the International Fiscal Association (Singapore Branch) in 2025 further highlights that unmanaged remote work arrangements can expose companies to “permanent establishment” risks in foreign jurisdictions if proper tax clearance procedures are not followed. As such, employers must treat overseas remote work during notice periods as a tax event, ensuring timely IR21 filing and strict withholding to remain compliant with IRAS regulations.

    Consequences of Non-Compliance

    Is the employer legally liable for the employee’s tax? Yes. If an employer fails to comply with tax clearance regulations, they face three primary risks:

    1. Financial Penalties: A fine of up to S$5,000 for non-filing or late filing.
    2. Direct Liability: If you fail to withhold monies and the employee leaves without paying, IRAS can recover the unpaid tax directly from your company’s bank account.
    3. Travel Restrictions: IRAS may issue a “Stop Order” to the ICA, preventing the employee from leaving Singapore until the tax is cleared. This often leads to legal disputes between the employee and the employer.

    About Koobiz Services

    Navigating the complexities of tax clearance for foreign employees is just one facet of maintaining a compliant and efficient business in Singapore. At Koobiz, we specialize in providing end-to-end corporate solutions designed for the modern 2026 economy. Our expertise ensures that your HR and accounting departments operate without the fear of IRAS penalties or regulatory bottlenecks.

    Our core services include:

    • Company Formation: Expert guidance on setting up your legal entity in Singapore, tailored for international founders. Learn more at koobiz.com
    • Tax & Accounting: Comprehensive management of corporate tax, GST, and individual tax clearance (IR21) for your workforce.
    • Banking Advisory: Assisting with the opening and maintenance of corporate bank accounts in Singapore’s premier financial institutions.
    • Corporate Secretary: Ensuring your company meets the highest standards of accuracy and compliance with ACRA and IRAS.

    Whether you are a startup hiring your first foreign employee or a multinational managing a large-scale retrenchment, Koobiz provides the precision and assurance your business needs to thrive. Visit us at koobiz.com to consult with our corporate tax and HR specialists today.

  • Determine Your Singapore Tax Residency: 2026 Guide for Expats & Companies

    Determine Your Singapore Tax Residency: 2026 Guide for Expats & Companies

    Advisory Note: Information is current as of January 2026. Tax regulations are subject to change; always verify with the Inland Revenue Authority of Singapore (IRAS) for the latest updates.

    [SUMMARIES]

    Individual Status: Determined primarily by the 183-day rule, with additional concessions for stays straddling 2 or 3 calendar years.

    Corporate Status: Hinges on the “Control and Management” test, focusing on where the Board of Directors makes strategic decisions.

    Tax Advantages: Residents benefit from progressive tax rates (0–24%), personal tax reliefs, and full access to Singapore’s extensive DTA network.

    Compliance: 2026 updates require stricter economic substance requirements for foreign-owned entities and physical presence for virtual board meetings to maintain residency.

    [/SUMMARIES]

    Determining your tax residency in Singapore is a foundational step for any expat or business owner looking to optimize their fiscal obligations in 2026. Whether you are a professional moving on an Employment Pass or a multinational establishing a regional hub, your residency status dictates your tax rates, eligibility for exemptions, and access to international treaties. Koobiz offers this comprehensive guide to help you navigate the complexities of Inland Revenue Authority of Singapore (IRAS) regulations, ensuring your financial planning remains both compliant and efficient.

    This guide distinguishes between the rules governing individuals and corporate entities. We explore the specific criteria that qualify a person or a company as a Singapore tax resident, the advantages of holding a Certificate of Residence (COR), and how Koobiz can streamline the application process for you.

    What Defines Individual Tax Residency in Singapore for 2026?

    183-day tax residency rule in Singapore
    183-day tax residency rule in Singapore

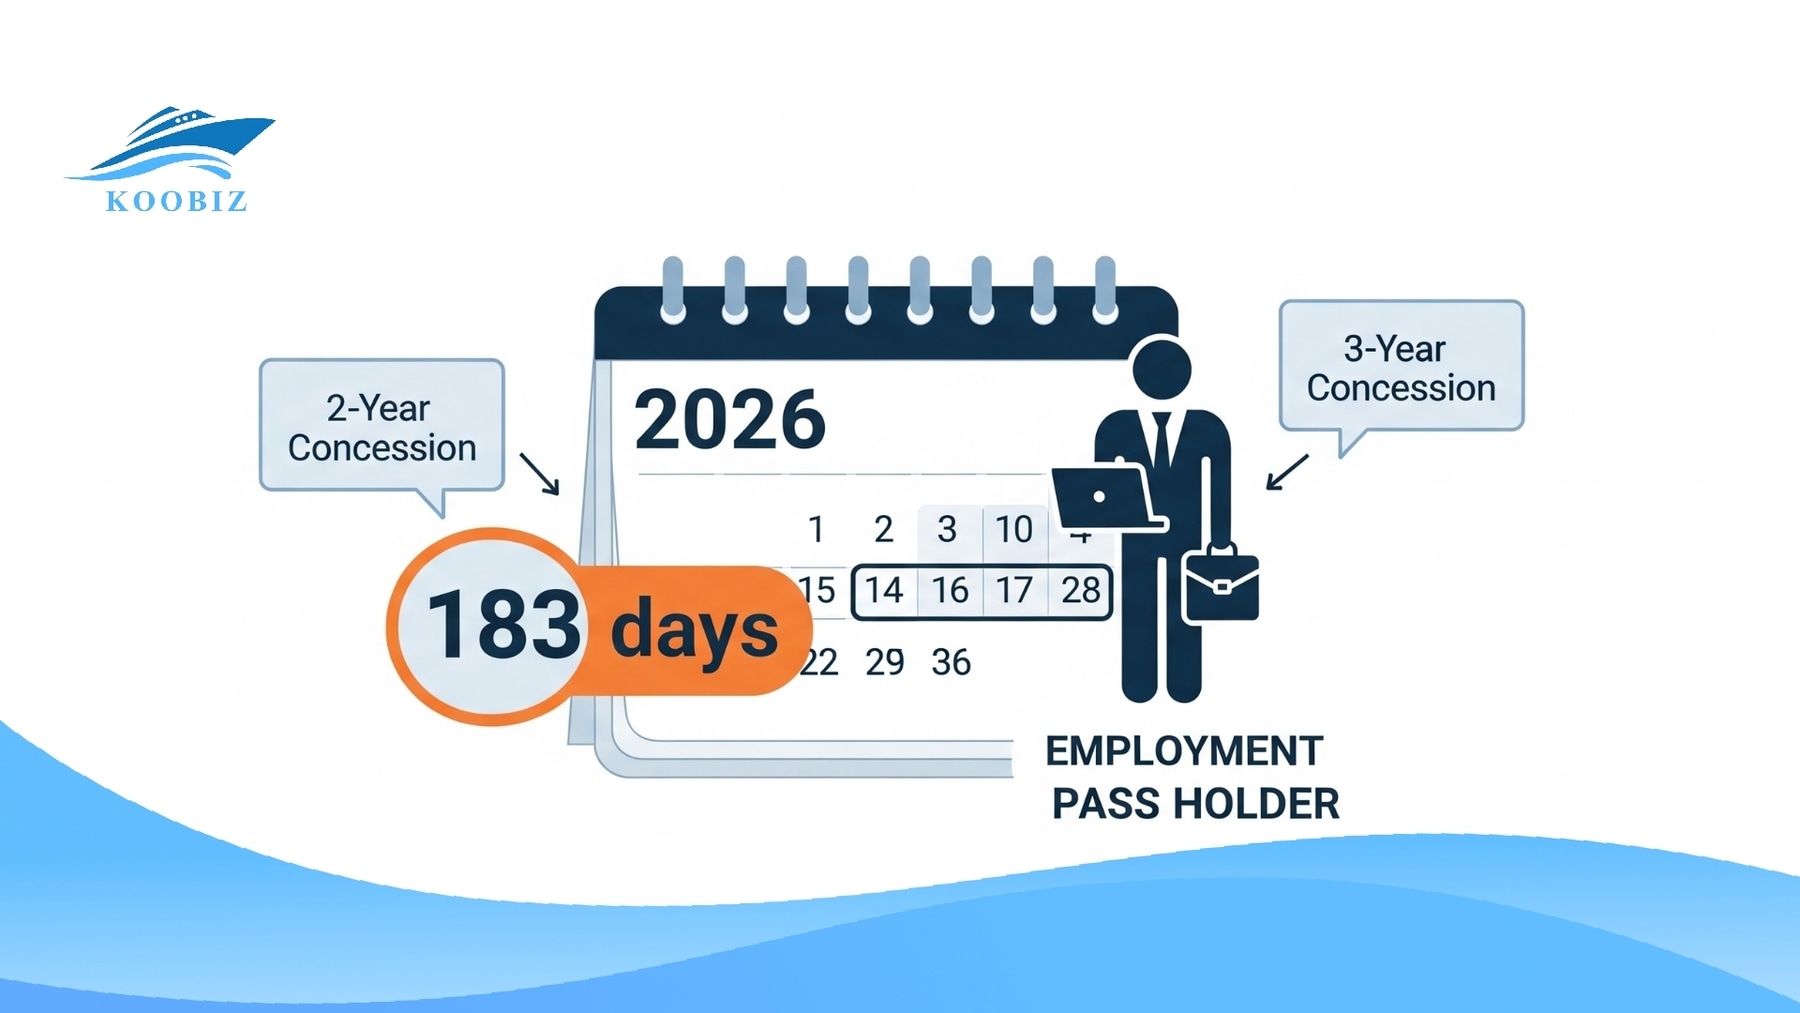
    A Singapore tax resident is generally defined as a Singapore Citizen or Permanent Resident who resides in Singapore, or a foreign individual who stays or works in Singapore for at least 183 days in a calendar year.

    Individual tax residency is crucial because it determines whether you are taxed at progressive resident tax rates or a flat non-resident rate. Importantly, tax residency status is reviewed annually and reassessed for each Year of Assessment (YA).

    The 183-Day Rule: Quantitative Presence

    The most common way for foreigners to qualify for Singapore tax residency is by meeting the 183-day quantitative threshold. This rule counts the total number of days you are physically present in the country during a calendar year (January 1 to December 31).

    • Inclusion of partial days: Any stay for even part of a day counts as a full day.
    • Work-related travel: Days spent outside Singapore for business travel or personal leave may still be counted toward the 183 days, provided your primary employment is based in Singapore.
    • Public holidays and weekends: These are fully included in the count.

    According to a 2025 study by the Singapore Tax Academy, over 85% of Employment Pass holders qualify as Singapore tax residents under the 183-day rule, enabling access to lower progressive tax rates.

    Administrative Concessions: The 2-Year and 3-Year Rules

    For individuals whose employment spans across two or three calendar years, IRAS provides specific administrative concessions. These are particularly useful for those who arrive late in the year and do not meet the 183-day requirement for that specific year but remain in Singapore for a significant duration thereafter.

    Concession Qualification Criteria Residency Outcome
    2-Year Concession Stay or work in Singapore for at least 183 days in total over two continuous calendar years. Considered a tax resident for both years.
    3-Year Concession Stay or work in Singapore for three consecutive years, even if the 183-day test is not met in the first or third year. Considered a tax resident for all three years.

    In practice, these concessions are commonly applied to help individuals obtain tax clearance and claim excess tax refunds. More specifically, these rules ensure that short-term assignments do not unfairly penalize foreigners with higher non-resident flat tax rates.

    Special Considerations: Digital Nomads and Retirees

    As work patterns evolve, IRAS has clarified rules for non-traditional residents. The table below outlines how Singapore tax residency is assessed for these groups:

    Profile Residency Trigger Key Tax Implication
    Digital Nomads Physical presence of 183 days or more in a calendar year while working remotely. Income derived from employment exercised in Singapore is generally considered Singapore-sourced and taxable.
    Retirees Qualitative factors, such as establishing a permanent home or intention to settle. Generally exempt from tax on foreign-sourced income (FSIE) and capital gains, making it highly tax-efficient.

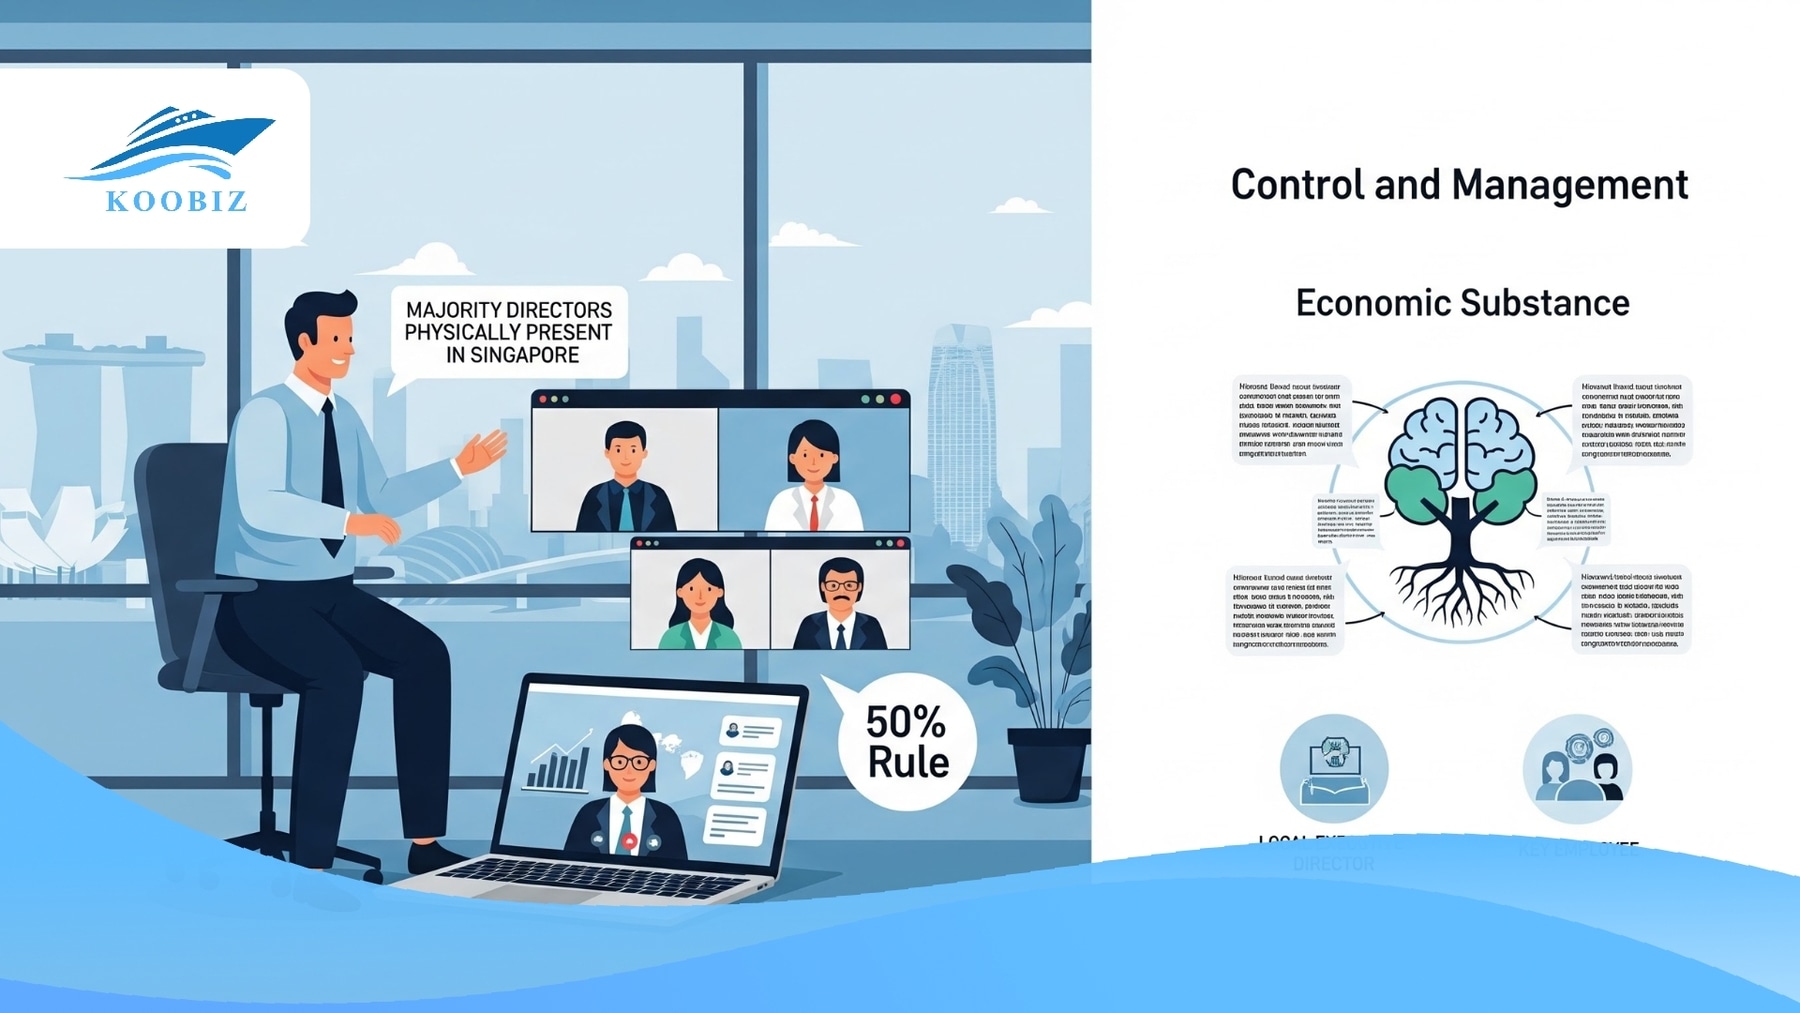
    Corporate Tax Residency in Singapore: The “Control and Management” Test

    Corporate tax residency control and management rule in Singapore
    Corporate tax residency control and management rule in Singapore

    A Singapore tax resident company is a corporate entity where the “control and management” of its business is exercised within Singapore. In practice, this refers to where the Board of Directors convenes to make strategic and high-level decisions, rather than where day-to-day operations are carried out.

    Additionally, the residency of a company is not determined solely by its place of incorporation. As a result, a company incorporated in Singapore may still be treated as a non-resident if its strategic decisions are made outside Singapore (e.g., at a foreign parent company’s headquarters).

    Virtual Board Meetings: 2026 Physical Presence Rules

    From 2026 onward, IRAS has clarified its position on the impact of virtual board meetings on corporate tax residency. While digital meetings are permitted, tax residency in Singapore is only maintained if a significant portion of the decision-making process remains anchored in the city-state.

    • The 50% Rule: According to explicit IRAS Guidance, at least 50% of the voting directors must be physically present in Singapore during the virtual meeting to validate that strategic decisions are made locally.
    • Chairman’s Location: Alternatively, the Chairman of the Board must be physically in Singapore to lead the strategic discussion.
    • Local Quorum: A Singapore-based quorum must be established to demonstrate that the company’s “nerve centre” is located in Singapore.

    Stricter Rules for Foreign-Owned Investment Holding Companies

    For foreign-owned investment holding companies, the bar for residency is higher. IRAS requires these entities to demonstrate “Economic Substance” to prevent the use of Singapore as a conduit for tax avoidance.

    In practice, for a holding company to be granted a Certificate of Residence (COR), it is expected to employ at least one Singapore-resident executive director and one local key employee, such as a CFO or senior manager. According to a 2026 compliance report by the Ministry of Finance, these substance requirements have been tightened to align with global BEPS 2.0 standards, ensuring that only genuine business operations benefit from Singapore’s tax treaties.

    Comparison: Singapore Tax Resident vs. Non-Resident Tax Treatment (YA 2026)

    Singapore tax resident status offers access to progressive tax rates and a wide range of reliefs, while non-resident taxation is generally based on flat rates with limited exemptions.

    To illustrate the financial impact of your status, it helps to compare the specific tax liabilities for the 2026 Year of Assessment. The table below summarizes how residency status directly affects an individual’s tax exposure.

    Feature Tax Resident (2026) Non-Resident (2026)
    Employment Income Progressive (0% – 24%) Flat 15% or Resident Rate (Whichever is higher)
    Director’s Fees Progressive (0% – 24%) Flat 24%
    Personal Tax Reliefs Eligible (CPF, SRS, Life Insurance) Not Eligible
    Tax Rebates (e.g., SG60) Tax Resident (YA 2026) Non-Resident (YA 2026)
    Withholding Tax Generally not applicable Applicable to certain income types
    Foreign Sourced Income Exempt (with conditions) Generally exempt

    For example, a tax resident earning $100,000 may face an effective tax rate of approximately 5.6%, whereas a non-resident would be taxed at a flat 15% ($15,000). This drastic difference highlights why tax residency is highly sought after by high-earning professionals and business owners. Furthermore, residents can claim a wide range of reliefs, such as the Earned Income Relief and Spouse Relief, which further reduce the taxable base.

    According to data from IRAS Budget 2025, the increase of the top marginal tax rate to 24% for income exceeding $1 million affects only the top 1% of resident taxpayers, while the flat 24% rate for non-resident directors applies from the first dollar of income.

    How to Apply for a Singapore Certificate of Residence (COR) in 2026

    Required documents to apply for Singapore COR
    Required documents to apply for Singapore COR

    There are two main methods for obtaining a Certificate of Residence (COR), depending on whether you are applying as a business or an individual. Both methods result in an official document confirming tax residency, although the application channels differ.

    1. For Companies: Apply via the IRAS myTax Portal (Corporate Tax).
    2. For Individuals: Apply via the myTax Portal (Individual Income Tax).

    Once tax residency has been established, the next practical step is to apply for a Certificate of Residence (COR). This document is essential for claiming benefits under Singapore’s 90+ Double Taxation Agreements (DTAs).

    Documentation Requirements for Companies

    Applying for a COR as a company requires rigorous documentation to prove that control and management are local. Koobiz typically assists clients in preparing the following supporting documents:

    • Board Minutes: Detailed records showing that strategic decisions were made in Singapore.
    • Attendance Logs: Proof of physical presence of directors during board meetings.
    • Economic Substance Evidence: Employment contracts for local staff and local office rental agreements.
    • Financial Statements: To show that the company is actively engaged in business.

    In summary, while the COR application process is digital, the underlying economic substance ultimately determines approval. According to research by the International Fiscal Association (Singapore Branch) in 2025, COR rejection rates for shell companies increased by 30% due to the lack of local executive directors.

    Emerging Compliance: BEPS 2.0 and Economic Substance in 2026

    Corporate tax compliance in Singapore: BEPS, nominee directors, VCC
    Corporate tax compliance in Singapore: BEPS, nominee directors, VCC

    A company may be subject to the 15% Global Minimum Tax if it belongs to a Multinational Enterprise (MNE) group with consolidated annual revenues exceeding €750 million.

    Regarding the global tax landscape, Singapore has implemented the Domestic Top-up Tax (DTT) and the Income Inclusion Rule (IIR) as part of the BEPS 2.0 Pillar Two framework. As a result, even where Singapore tax residency is established, the effective tax rate may be “topped up” to 15% for entities within large MNE groups.

    The Impact of Nominee Directors on Singapore Tax Residency Status

    A common pitfall for foreign investors is relying solely on a nominee director to satisfy Singapore tax residency requirements. While a nominee director fulfills the legal requirement of the Companies Act, IRAS often views this as insufficient for “Control and Management.”

    In particular, where a nominee director lacks genuine decision-making authority and merely follows instructions from offshore owners, IRAS may deny the issuance of a Certificate of Residence (COR). Koobiz recommends appointing at least one resident Executive Director who is actively involved in the company’s strategic direction to safeguard your tax residency status.

    Singapore Tax Residency for Variable Capital Companies (VCCs)

    The Variable Capital Company (VCC) is a specialised corporate structure commonly used by fund managers and investment vehicles.

    • Single Tax Residence: Even if a VCC has multiple sub-funds, it only needs to satisfy the control and management test once at the umbrella level.
    • Sub-fund Benefits: Once the umbrella VCC is deemed a resident, all its sub-funds can enjoy the benefits of Singapore’s DTA network.

    This structure makes the VCC an incredibly efficient vehicle for regional investment. According to the Monetary Authority of Singapore (MAS) 2025 Year-End Review, the “umbrella-level residency” rule has been a key driver behind the 40% growth in VCC registrations among Asian family offices.

    Common Singapore Tax Residency Myths and FAQs

    There are 4 main myths surrounding tax residency in Singapore: the “60-day rule” exemption, the impact of remote work, the status of Singapore citizens abroad, and the permanence of residency status.

    To clarify these misconceptions, it is necessary to examine several common edge cases that frequently cause confusion among taxpayers. The sections below address these scenarios by outlining the relevant characteristics and qualifying factors.

    Myth 1: Working in Singapore for less than 60 days means no tax liability.

    Reality: While you may be exempt from tax on employment income if you work in Singapore for 60 days or less, this does not apply to company directors or public entertainers. In addition, directors’ fees are taxed at a flat rate of 24%, regardless of the number of days spent in Singapore.

    Myth 2: Remote work for a foreign company does not count as Singapore-sourced income.

    Reality: If you are physically located in Singapore while performing your work, that income is generally considered sourced in Singapore. If you remain in Singapore for more than 183 days while working remotely, you are generally treated as a tax resident and may be required to report foreign-sourced income remitted into Singapore, subject to the FSIE rules.

    Myth 3: Singapore citizens are always treated as tax residents.

    Reality: Tax residency is determined based on whether an individual is “ordinarily resident” in Singapore. For example, a Singapore citizen who lives and works permanently in London and visits Singapore only briefly each year would likely be treated as a non-resident for that specific Year of Assessment.

    Myth 4: Once classified as a tax resident, residency status is permanent.

    Reality: Residency status is not permanent. It is reviewed on a yearly basis. If you move away or your company moves its board meetings to another country, your tax residency in Singapore can be lost in the following year.

    According to a 2025 study by the Tax Governance Institute, nearly 20% of remote workers in Singapore incorrectly assumed they were exempt from local filing, leading to significant penalties during IRAS audits.

    About Koobiz Services

    At Koobiz, we specialise in the intricacies of the Singapore business ecosystem. Our mission is to provide seamless advisory services for entrepreneurs and corporations looking to thrive in one of the world’s most competitive tax environments.

    Our core services include:

    • Company Formation: Expert guidance on setting up your Singapore entity to ensure immediate compliance and optimal structure for tax residency in Singapore.
    • Banking Account Advisory: Strategic support in opening and maintaining corporate bank accounts in Singapore’s leading financial institutions.
    • Tax & Accounting: Comprehensive tax planning, GST filing, and Year of Assessment preparation to maximise your reliefs and minimize liabilities.
    • Corporate Secretarial Services: Ensuring your company structure and board decisions meet all economic substance requirements.

    For personalised assistance with your Certificate of Residence application or to review your corporate substance requirements for 2026, contact our experts at koobiz.com today.

  • Understand What Is TIN Number in Singapore: NRIC, FIN and UEN Explained

    Understand What Is TIN Number in Singapore: NRIC, FIN and UEN Explained

    [SUMMARIES]

    Unified Identity: In Singapore, your TIN is generally your NRIC (for citizens/PRs), FIN (for foreigners), or UEN (for businesses).

    No Application Needed: Most residents and entities are automatically assigned these numbers upon registration; separate tax numbers are rare.

    Global & Local Use: This number is mandatory for local tax filing, opening bank accounts, and international forms like the US W-8BEN.

    Instant Verification: You can retrieve and verify your TIN securely via the Singpass app or the myTax Portal.

    [/SUMMARIES]

    Navigating local compliance in Singapore starts with one key question: what is a TIN number? In 2026, the Tax Identification Number (TIN) is the digital DNA of your fiscal identity, used by the Inland Revenue Authority of Singapore (IRAS) to track tax obligations. Whether you are an individual or a business partner of Koobiz, your TIN is the gateway to financial services.

    Singapore streamlines this by using existing IDs—NRIC for locals and UEN for businesses—as the official Tax Reference Number (TRN). Below, we explore the definitions and applications of these numbers to ensure you remain fully compliant.

    What is a TIN Number in the Singapore Context?

    A Tax Identification Number (TIN) is a unique alphanumeric identifier issued by a national tax authority to track tax obligations, income, and government identification for individuals and business entities. In Singapore, the term “TIN” is technically referred to as the Tax Reference Number (TRN), which is used by IRAS for all income tax, GST, and corporate tax matters.

    The TIN is a core identifier for fiscal interactions, ensuring that all transactions—from employment income to corporate distributions—are attributed to the correct legal person. In the 2026 Singapore’s digital economy, your TIN is integrated into the national Singpass ecosystem and functions as a key underlying component of your financial administration.

    Is the TIN different from my NRIC or FIN?

    For the vast majority of individuals residing in the Lion City, the TIN is not a separate number you need to apply for; rather, it is your NRIC (National Registration Identity Card) or FIN (Foreign Identification Number). Singapore citizens and Permanent Residents (PRs) use their NRIC as their default TIN, whereas foreign professionals holding Employment Passes or S-Passes use their FIN for tax identification purposes.

    This integrated ID system significantly reduces administrative errors compared to countries that maintain separate social security and tax identification registries, streamlining cross-border verification.

    The Role of TIN in 2026 Financial Transactions

    The TIN functions as the primary identifier for all financial transactions and is relied upon by banks and government agencies. It is required for opening personal bank accounts, making CPF (Central Provident Fund) contributions, and accessing government subsidies such as GST vouchers or the Assurance Package.

    As banking security evolves, the TIN is now verified instantly via real-time API calls to the MyInfo database. This means that when you provide your NRIC or FIN to a financial institution, they are simultaneously verifying your tax residency and identity status to ensure compliance with Anti-Money Laundering (AML) laws.

    Identification of TIN Types: Individual vs. Business

    There are three main types of identification numbers in Singapore categorized by the residency status of the individual or the legal nature of the entity. Identifying which category you fall into is essential because using the wrong format can lead to rejected tax filings or delays in business operations.

    TIN Type Full Name Category Primary Audience
    NRIC National Registration Identity Card Individual Singapore Citizens & Permanent Residents
    FIN Foreign Identification Number Individual Foreigners (EP, S-Pass, Long-term Pass)
    UEN Unique Entity Number Business Registered Companies, LLPs, Societies

    Identifying the correct TIN type is the first thing our consultants at Koobiz verify when assisting clients with company formation or tax advisory. Transitioning from individual status to business ownership requires a shift in which number you use for different fiscal purposes.

    For Singapore Citizens and PRs: The NRIC

    The NRIC is the primary identification number for all Singaporeans, and it follows a specific format that denotes the era of the holder’s birth or registration, followed by seven digits and a final checksum letter (e.g., S1234567A).

    • Prefix S: Used for citizens and PRs born before January 1, 2000.
    • Prefix T: Used for citizens and PRs born on or after January 1, 2000.

    Your NRIC remains your TIN as long as you maintain your citizenship or residency status.

    For Foreign Professionals: The FIN

    The Foreign Identification Number (FIN) is assigned to foreigners who have a long-term pass by the Ministry of Manpower (MOM) or the Immigration and Checkpoints Authority (ICA). The FIN system now utilizes three main prefixes to manage the volume of residents.

    • Prefix F: Issued to foreigners who were granted passes before January 1, 2000.
    • Prefix G: Issued to foreigners who were granted passes between January 1, 2000, and December 31, 2021.
    • Prefix M: The newest series introduced on January 1, 2022, to accommodate the increasing number of foreign professionals in the digital and tech sectors.

    For Corporate Entities: The Unique Entity Number (UEN)

    The Unique Entity Number (UEN) is the 9 or 10-digit identification number for all registered entities in Singapore, including local companies, LLPs, and societies. For businesses, the UEN serves as the single identifier for interactions with ACRA, IRAS, and Singapore Customs.

    How to Find and Verify Your TIN in 2026

    Finding your TIN in Singapore is straightforward depending on your identification status and access to digital government services. For most residents, if you hold a valid identity card or work pass, you already have a TIN. For Koobiz clients, tax information no longer requires manual record searches. The following step-by-step guides are the most efficient ways to retrieve and verify your number.

    Do I Need to Apply for a Separate TIN?

    The answer is No for most individuals and businesses because the TIN is automatically issued upon the successful registration of your identity or entity. However, there are rare exceptions where IRAS may issue an “ASGD” (Assigned) number for specific cases where an individual is not eligible for an NRIC or FIN but has tax obligations in Singapore.

    If you are a non-resident who owns property in Singapore and derives rental income, you may need to apply for an Income Tax Reference Number through the IRAS portal. In summary, if you have a Singpass account, you already have a TIN; if you are an overseas investor without an ID, you must contact IRAS to have a number assigned.

    Step-by-Step Retrieval Guide

    If you need to retrieve your TIN for an official form or banking application, follow the steps below corresponding to your status.

    For Individuals (Using Singpass App)

    1. Launch App: Open the Singpass app on your mobile device.
    2. Access Digital IC: Tap on the Digital IC card located on the home screen.
    3. Authenticate: Use your fingerprint, face ID, or passcode to verify your identity.
    4. Reveal: Tap the “Show details” button or the eye icon next to the masked number. This unmasked NRIC or FIN is your official Tax Reference Number.

    For Businesses (Using myTax Portal)

    1. Visit Portal: Go to mytax.iras.gov.sg.
    2. Log In: Select “Business Tax” and log in using your Singpass (Corppass) credentials.
    3. Select Entity: If you are an authorized officer for multiple entities, select the correct UEN from the dropdown list.
    4. View Dashboard: Your company’s UEN and current tax balance will be displayed clearly at the top of the dashboard.

    For Public Verification (Checking a Vendor)

    1. Visit Directory: Go to uen.gov.sg or bizfile.gov.sg.
    2. Search: Enter the company name in the search bar.
    3. Verify: The system will display the valid UEN and entity status (e.g., “Live”), confirming the business is registered and active.

    Understanding TIN Formats and Checksum Verification

    Comparing TIN formats is essential to distinguish between individual and corporate identifiers and avoid errors in official documentation. While all TINs in Singapore are alphanumeric, the individual format (NRIC/FIN) and the business format (UEN) follow distinct structures that reflect their administrative origins.

    Understanding these formats allows you to manually verify if a number is valid before submitting it for a cross-border transaction. Meanwhile, at Koobiz, we use automated tools to validate every UEN or FIN provided by our clients for absolute accuracy.

    Individual Format: #0000000@

    The individual format (NRIC and FIN) always consists of nine characters: one prefix letter, seven digits, and one trailing checksum letter. The seven digits are a unique serial number, while the final letter is calculated based on a mathematical formula to prevent transcription errors.

    To illustrate, an NRIC might look like S1234567A. The trailing letter ‘A’ is not random; it is the result of a specific weightage applied to the digits. This format is recognized worldwide by financial institutions, ensuring that your tax identity is unique and verifiable across international borders.

    Business Format: YYYYNNNNNC vs. NNNNNNNNC

    Older entities (registered before 2009) typically have an 8-digit number followed by a letter, while newer entities use a 10-character string that begins with the year of registration.

    Criteria Old UEN Format Modern UEN Format (Post-2009)
    Length 9 Characters 10 Characters
    Structure NNNNNNNNC (e.g., 12345678A) YYYYNNNNNC (e.g., 202612345G)
    Advantage Simplified for older systems High transparency (Year of birth)

    The modern 10-digit UEN is now the standard for new businesses, immediately identifying them as contemporary entities.

    Checksum Calculation Basics

    Verifying a TIN often involves a checksum calculation. While the specific algorithms are technical, understanding the logic helps in spotting obvious errors.

    TIN Type Format Example Checksum Logic
    NRIC/FIN S1234567A Weighted sum of digits + prefix offset, Modulo 11 determines the letter.
    UEN (Old) 12345678A Weighted sum of digits, Modulo 11 determines the final letter.
    UEN (New) 202612345G Year prefix + Serial Number + Weighted Modulo 11 check.

    Global Compliance and the 2026 Regional Shift

    In the globalized world of 2026, your Singaporean TIN is not just for local use; it is a critical component of international tax compliance. Specifically, your TIN wins on cross-border transparency, while neighboring countries’ systems are still catching up to the optimal ID Convergence model that Singapore has mastered.

    Let’s look at how the TIN interacts with foreign tax authorities and the emerging trends in Southeast Asia. This transition from a purely local identifier to a global compliance tool of a firm like Koobiz becomes invaluable for expat entrepreneurs and multinational corporations.

    Using your Singapore TIN for US Tax (Form W-8BEN)

    For Singapore-based freelancers or investors receiving income from the United States, providing your NRIC or FIN as a “Foreign Tax Identifying Number” on Form W-8BEN—while establishing your Singapore tax residency—is mandatory. This allows you to claim tax treaty benefits (if applicable) and prevents the US Internal Revenue Service (IRS) from withholding the standard 30% of your income.

    Providing your UEN as the TIN is recommended as a Business Entity. Following the implementation of enhanced reporting standards, failure to provide a valid TIN often results in an automatic freeze of US-sourced payments until the identity is verified.

    Regional Trend: Vietnam’s PIN Transition (2025-2026)

    One of the most significant shifts in the region is the Vietnam PIN Transition, which officially replaced dedicated tax codes with a 12-digit Personal Identification Number (PIN) starting July 1, 2025. By 2026, this system will be fully implemented, mirroring Singapore’s model of using a single ID for all government interactions.

    As of 2026, this streamlined system is easing the administrative burden on cross-border business setups and facilitating faster entity verification across the region.

    TIN and the Common Reporting Standard (CRS)

    The TIN is the primary data point exchanged under the Common Reporting Standard (CRS), a global framework for the automatic exchange of financial account information. Singapore, along with over 100 other jurisdictions, uses the TIN to ensure all residents with offshore accounts are accurately reporting their income to their home tax authority.

    In summary, your TIN is the link that connects your bank accounts worldwide to your tax residency in Singapore. Tax authorities increasingly use data matching algorithms to flag discrepancies between global account balances and reported income using the TIN as the primary search key.


    About Koobiz Services

    At Koobiz, we understand that navigating tax identification and compliance is the backbone of a successful business. Our team of specialists provides end-to-end support for entrepreneurs and corporations looking to establish or optimize their presence in Singapore and beyond.

    Our core services include:

    • Company Formation: Seamless incorporation in Singapore, including immediate UEN/TIN issuance. Learn more about starting a business
    • Banking Account Advisory: Assistance in opening corporate bank accounts in Singapore with full KYC and TIN documentation support.
    • Tax and Accounting: Comprehensive tax filing services for individuals and businesses, ensuring you leverage all available deductions.
    • Audit and Compliance: Keeping your entity in good standing with IRAS and ACRA through professional corporate secretarial services.

    Visit koobiz.com to schedule a consultation with our corporate advisory specialists today.

    Disclaimer: This article is for general informational purposes only and does not constitute professional legal or tax advice. Regulations and tax laws are subject to change. Please consult with the Inland Revenue Authority of Singapore (IRAS) or a qualified tax professional at Koobiz for advice specific to your situation. Last updated: May 2026.

  • Singapore Tax Bracket 2026: Latest Personal Income Tax Rates

    Singapore Tax Bracket 2026: Latest Personal Income Tax Rates

    [SUMMARIES]

    Singapore utilizes a progressive tax system for residents with rates ranging from 0% to 24%, while non-residents are subject to flat rates or higher tax liabilities.

    Tax residency determines eligibility for tax reliefs and is generally established by staying or working in Singapore for at least 183 days in a calendar year.

    Filings must be submitted by mid-April annually, and failure to comply can result in financial penalties, estimated assessments, or legal enforcement.

    [/SUMMARIES]

    Understanding Singapore tax brackets is key to knowing how much tax you really pay. This 2026 guide explains the latest personal income tax rates, how the progressive system works, and what they mean for residents and non-residents.

    What Is a Singapore Tax Bracket?

    A Singapore tax bracket is a range of income taxed at a specific rate under Singapore’s progressive personal income tax system. Instead of taxing your entire income at one rate, Singapore applies higher tax rates only to higher portions of income.

    This means lower-income portions are taxed at lower rates, while income above certain thresholds is taxed at higher rates. The system mainly applies to tax residents, while non-residents are subject to different tax rules and rates.

    Overall, Singapore’s tax bracket system is simple, transparent, and taxpayer-friendly, helping keep personal income tax relatively low for most individuals.

    How Singapore’s Progressive Income Tax System Works

    Understanding Progressive Taxation in Singapore
    Understanding Progressive Taxation in Singapore

    Singapore uses a progressive income tax system, meaning your tax rate increases as your income increases. However, the higher tax rates apply only to the portion of income within each tax bracket, not to your entire income.

    Each level of income is taxed separately, starting from the lowest rate and moving upward. As a result, even high-income earners continue to enjoy lower tax rates on the first portions of their income.

    This system helps balance fairness and efficiency: lower- and middle-income earners face a lighter tax burden, while higher-income individuals contribute more in absolute terms. It also ensures that Singapore’s personal income tax system remains predictable, transparent, and competitive by global standards.

    The exact tax rates and income thresholds depend on whether you are classified as a tax resident or non-resident, which is explained in the next sections.

    Singapore Personal Income Tax Brackets 2026 (Latest Update)

    Singapore Tax Brackets for Tax Residents

    For tax residents in Singapore, personal income tax is charged at progressive rates that increase with chargeable income. As of the Year of Assessment (YA), resident tax rates range from 0% to 24%.

    Below is an overview of the Singapore resident tax brackets:

    Chargeable Income Income Tax Rate (%) Gross Tax Payable ($)
    First $20,000 0 0
    Next $10,000 2 200
    First $30,000 200
    Next $10,000 3.5 350
    First $40,000 550
    Next $40,000 7 2,800
    First $80,000 3,350
    Next $40,000 11.5 4,600
    First $120,000 7,950
    Next $40,000 15 6,000
    First $160,000 13,950
    Next $40,000 18 7,200
    First $200,000 21,150
    Next $40,000 19 7,600
    First $240,000 28,750
    Next $40,000 19.5 7,800
    First $280,000 36,550
    Next $40,000 20 8,000
    First $320,000 44,550
    Next $180,000 22 39,600
    First $500,000 84,150
    Next $500,000 23 115,000
    First $1,000,000 199,150
    In excess of $1,000,000 24

    Singapore Tax Rates for Non-Residents

    For non-residents, personal income tax is applied differently than for tax residents:

    • Employment Income: Taxed at a flat rate of 15% or the progressive resident tax rates, whichever results in a higher tax amount.
    • Other Income: Income such as director’s fees, consultancy fees, and rental income is generally taxed at a flat rate of 24% (from YA 2024 onwards), unless a reduced withholding tax rate applies under a tax treaty.
    • Withholding Tax: Certain payments to non-residents are subject to withholding tax, with rates depending on the nature of the income and the specific Year of Assessment.

    Additionally, non-residents are ineligible for personal tax reliefs. Consequently, their chargeable income is often higher than that of residents, as fewer deductions can be claimed to offset the total amount.

    How to Determine Your Tax Residency Status

    Your tax residency status in Singapore determines the applicable tax rates and your eligibility for personal tax reliefs. This status is primarily based on the duration of your stay or employment within a calendar year.

    How Tax Residency Is Determined in Singapore
    How Tax Residency Is Determined in Singapore

    You are generally treated as a tax resident if:

    • You are a Singapore Citizen or Permanent Resident who resides in Singapore.
    • You are a foreigner who has stayed or worked in Singapore for at least 183 days in a calendar year.
    • You work in Singapore for a continuous period spanning three consecutive calendar years, even if your stay is less than 183 days in the first or third year.
    • You work in Singapore across two calendar years with a total stay of at least 183 days (including time immediately before and after employment). Note: This administrative concession applies to employees and excludes directors, public entertainers, and professionals.

    If none of the above conditions are met, you will be classified as a non-resident, and different tax rules and rates will apply.

    How to Reduce Your Taxable Income (Legal Tax Reliefs)

    Singapore offers various legal tax reliefs to help reduce your chargeable income and overall tax payable. These reliefs mainly apply to tax residents and are deducted before income tax is calculated.

    Common tax reliefs include:

    • Earned Income Relief for employed and self-employed individuals
    • CPF Relief for mandatory and voluntary CPF contributions
    • Family Reliefs (Parent, Spouse, and Child Reliefs) for supporting eligible dependants
    • Course Fees Relief for approved, career-related training and education
    • Life Insurance Relief, subject to qualifying conditions

    Each relief has specific eligibility requirements and caps. In addition, total personal income tax relief is capped at $80,000 per Year of Assessment, ensuring fair and reasonable claims.

    Filing Your Taxes: Deadlines & Penalties

    In Singapore, personal income tax returns must be filed annually with the Inland Revenue Authority of Singapore (IRAS). The statutory deadlines are 15 April for paper submissions and 18 April for e-filing.

    If you are placed under the No-Filing Service (NFS) scheme, you are not required to file a return. However, it remains your responsibility to verify the accuracy of your auto-generated tax assessment and inform IRAS of any discrepancies.

    Failure to file on time may lead to:

    • Late filing penalties and composition fees.
    • Estimated tax assessments issued by IRAS, which may be higher than your actual liability.
    • Legal or enforcement actions for persistent non-compliance.

    To avoid these consequences, ensure you file early and verify your income details. Promptly responding to IRAS notices will help ensure a seamless process and prevent avoidable financial penalties.

    Example: How Income Tax Is Calculated Under Singapore Tax Brackets

    Sample Income Tax Calculation in Singapore
    Sample Income Tax Calculation in Singapore

    To illustrate how Singapore’s progressive income tax system works, let’s walk through a step-by-step example for a tax resident.

    Step 1: Determine Your Chargeable Income

    Assume an individual earns an annual salary of SGD 80,000 and qualifies for SGD 10,000 in personal tax reliefs.

    • Gross annual income: SGD 80,000
    • Less: personal tax reliefs: SGD 10,000
    • Chargeable income: SGD 70,000

    Step 2: Apply Progressive Tax Rates

    Singapore taxes income in “slices,” with each portion taxed at a different rate:

    • First SGD 20,000: 0% → SGD 0
    • Next SGD 10,000: 2% → SGD 200
    • Next SGD 10,000: 3.5% → SGD 350
    • Remaining SGD 30,000: 7% → SGD 2,100

    Step 3: Calculate Total Tax Payable

    Add the tax from each bracket:

    • SGD 0 + 200 + 350 + 2,100 = SGD 2,650
    • Total income tax payable: SGD 2,650

    Step 4: Understand the Effective Tax Rate

    Although the highest marginal tax rate applied is 7%, the individual’s effective tax rate is much lower:

    SGD 2,650 ÷ SGD 80,000 ≈ 3.3%

    Key takeaway

    Under Singapore’s progressive tax brackets, higher tax rates apply only to higher portions of income, not your entire salary. This keeps the overall tax burden low, fair, and competitive, even as income increases.

    Simplify Your Singapore Tax Filing with Koobiz

    Navigating Singapore’s personal income tax rules can be time-consuming, especially if you have multiple income sources, cross-border arrangements, or changing residency status. That’s where our accounting and tax experts step in.

    Koobiz provides end-to-end personal tax support for professionals and entrepreneurs, including:

    • Assessing your tax residency status accurately
    • Reviewing income sources and identifying eligible tax reliefs to maximize your savings
    • Preparing and filing your tax return flawlessly in line with IRAS requirements
    • Advising on tax optimization strategies while staying fully compliant

    Whether you are a local resident, expatriate, or foreign professional, Koobiz helps ensure your tax filing is accurate, timely, and stress-free—so you can focus on work and life in Singapore with confidence. Contact us today to secure a smoother tax experience and peace of mind during tax season.

  • How to Register for GST in Singapore: A Step-by-Step Guide (Updated for 2026)

    How to Register for GST in Singapore: A Step-by-Step Guide (Updated for 2026)

    [SUMMARIES]

    Mandatory Threshold: Registration is required if your business’s taxable turnover exceeds S$1 million. This is assessed either by looking back at the past calendar year or by forecasting the next 12 months.

    Voluntary Option: Businesses below the threshold can register voluntarily to reclaim GST on expenses. This requires a two-year commitment and the use of InvoiceNow-compatible software.

    Digital Process: Applications are submitted online through the myTax Portal using CorpPass. You’ll need documents like your ACRA business profile and bank details.

    Pre-Registration Claims: You may reclaim GST paid on certain business costs incurred up to 6 months before your registration date.

    Strict Compliance: Once registered, you must show prices inclusive of GST, file returns on time, and set up GIRO for payments (mandatory for voluntary registrants) to avoid penalties.

    [/SUMMARIES]

    Successfully registering for Goods and Services Tax (GST) is a key step for growing businesses in Singapore. The process can seem complex due to strict rules and compliance needs. At Koobiz, we understand that whether you are scaling up to meet the mandatory S$1 million turnover requirement or strategically opting for voluntary registration to optimize your tax position, getting the registration right is paramount.

    To help you manage this transition smoothly, this guide provides a comprehensive walkthrough on how to register for GST in Singapore, covering the latest 2026 updates including the InvoiceNow mandate and annual assessment rules.

    IMPORTANT UPDATES FOR 2026

    Before proceeding, be aware of two critical changes to the GST regime:

    InvoiceNow Mandate for Voluntary Registration:

    • From 1 November 2025: New companies (applying within 6 months of setup) that register voluntarily must use InvoiceNow-ready software to send invoice data to IRAS.
    • From 1 April 2026: All new voluntary registrants must use InvoiceNow solutions. Applications may be rejected without this.

    Grace Period for Prospective Registration: For registration liabilities arising on or after 1 July 2025, IRAS offers a 2-month grace period for the registration effective date, giving you more time to prepare.

    Do You Need to Register for GST?

    Financial report exceeding the S$1 million threshold
    Financial report exceeding the S$1 million threshold

    Yes, you must register for GST if your business’s taxable turnover exceeds S$1 million under either the retrospective or prospective view.

    Accurate liability assessment requires calculating your “Taxable Turnover,” not merely reviewing total bank deposits. This figure is defined by the specific inclusion of certain revenue streams and the exclusion of others.

    What Counts Towards Taxable Turnover?

    IRAS requires you to sum up the following income sources to see if you hit the S$1 million threshold:

    • Standard-Rated Supplies (9%): Most local sales of goods and services in Singapore (for example, retail purchases and consultancy fees).
    • Zero-Rated Supplies (0%): Goods exported overseas and international services provided to foreign clients.

    What is EXCLUDED from Taxable Turnover?

    Do not include these when calculating your S$1 million turnover:

    • Exempt Supplies: Financial services (such as interest income or share issues) and the sale or lease of residential properties.
    • Out-of-Scope Supplies: Sales where goods are delivered from outside Singapore to another place outside Singapore (third-country sales).
    • Sale of Capital Assets: Proceeds from selling major business assets like machinery or furniture.

    To determine whether you’ve crossed the S$1 million mark, you need precise calculations of these revenue streams. At Koobiz, we frequently help clients audit their revenue sources to avoid accidentally triggering a GST registration requirement.

    Why that registration matters: Failing to register when required is a serious offense in Singapore (penalty up to S$10,000 and 10% additional penalty). If you’re liable but don’t apply, IRAS may backdate your registration, forcing you to pay GST on past sales out of your own pocket.

    Compulsory vs. Voluntary Registration

    Compulsory registration is mandated by law based on revenue milestones, whereas voluntary registration is a strategic choice for businesses earning under the threshold.

    To help you decide or determine your mandatory vs. voluntary registration obligations, here is a direct comparison of the two paths:

    Feature Compulsory Registration Voluntary Registration
    Who is it for? Businesses with taxable turnover > S$1 million. Businesses with taxable turnover < S$1 million.
    Trigger Mandated by law under the Retrospective (Annual) or Prospective view. Strategic choice by the business owner.
    Key Benefit Compliance with the law (avoids penalties). Ability to claim input tax (refunds) on business expenses.
    Key Obligation Must register within 30 days of liability notification date. Must commit to remaining registered for at least 2 years.
    New Requirement Must be ready to charge GST. Must use InvoiceNow solutions (phased implementation).
    Risk Late registration attracts backdated taxes and fines. Administrative costs and GIRO requirement.

    Retrospective View vs. Prospective View (Compulsory)

    If you’re under the compulsory regime, you use one of these tests to determine when to register:

    1. Retrospective View (Annual Assessment): You must register if your taxable turnover for the calendar year (1 Jan to 31 Dec) exceeds S$1 million.
      • Deadline: You have until 30 January of the following year to apply.
      • Effective Date: You will be registered for GST on 1 March of that year.
    2. Prospective View: You must register if you reasonably expect your taxable turnover to exceed S$1 million in the next 12 months. This typically applies if you have signed a large sales contract.
      • Deadline: You must apply within 30 days of the date of your forecast/signed contract.

    Businesses can now monitor compliance more easily by reviewing the past calendar year (retrospective). For future-looking assessments (prospective), IRAS requires formal documentation like purchase orders or signed contracts to support your forecasted figures.

    Voluntary Registration Considerations

    If you’re not required to register, the decision often comes down to cost versus benefit. Voluntary registration is especially advantageous for exporters (who sell zero-rated goods but incur GST on local costs) or start-ups with significant upfront capex.

    However, voluntary registration comes with conditions: you must stay GST-registered for at least two years, comply with all filing requirements, and set up GIRO payments for taxes and refunds. Also, with the InvoiceNow mandate starting November 2025 for new companies, you’ll need a compatible accounting system to transmit invoice data to IRAS as part of your application.

    Practical Case Studies: Determining Your Liability

    Applying the abstract rules of registration to concrete business scenarios helps clarify exactly when you need to act.

    To help you visualize whether your business falls under the mandatory or voluntary brackets, let’s examine three updated scenarios based on 2026 rules.

    Scenario 1: The Retrospective Trigger (Mandatory)

    Situation: TechFlow Solutions, a software consultancy, had steady revenue. By 31 December 2025, their accumulated revenue for the calendar year reached S$1.2 million.

    Verdict: They have triggered the Retrospective View.

    Action: TechFlow must apply for GST registration by 30 January 2026. Their GST registration will be effective from 1 March 2026.

    Note: They do not need to check their turnover at the end of every quarter, only at the end of the calendar year.

    Scenario 2: The Prospective Trigger (Mandatory)

    Situation: BuildStrong Construction is a new company. On 15 July 2025, they secure a confirmed contract worth S$1.5 million.

    Verdict: They have triggered the Prospective View.

    Action: They must apply within 30 days. Under the new rules for liabilities arising after 1 July 2025, IRAS allows a grace period. While they apply in August, their effective date might be set to 1 October 2025 (approx. 2 months later), giving them time to set up their invoicing systems.

    Scenario 3: The Strategic Choice (Voluntary)

    Situation: PureExport Trading (incorporated in Jan 2026) buys goods locally and exports them to Europe. Their annual turnover is only S$800,000.

    Verdict: They are not required to register.

    Action: However, they choose Voluntary Registration in April 2026 to claim input tax refunds. Because they are applying after 1 April 2026, they must adopt an InvoiceNow-ready solution to transmit invoice data to IRAS as part of their application approval conditions.

    Prerequisites for GST Registration

    Prerequisites for GST Registration Singapore
    Prerequisites for GST Registration Singapore

    There are three main categories of prerequisites: administrative access, business documentation, and educational requirements.

    Before logging into the portal, ensuring you have these elements ready will streamline the application process and prevent session timeouts.

    The e-Learning Course Requirement

    The most overlooked prerequisite is the “Overview of GST” e-Learning course. Business owners (sole proprietors, partners, or directors) applying under the Voluntary Registration scheme are generally required to complete this course.

    Exemptions apply if:

    • Your director/partner has already managed other GST-registered businesses, or
    • You engage a professional tax agent (like Koobiz) to handle your GST matters. Our affiliation can reassure IRAS of your compliance.

    Additional Voluntary Requirements (2026)

    • GIRO Account: You must have a GIRO application form processed or pending.
    • InvoiceNow: You must be prepared to declare your InvoiceNow-ready software details.

    By preparing your CorpPass (with “IRAS Digital Services” authorized), your ACRA Business Profile, and your bank account details for GIRO setup beforehand, you ensure a frictionless application experience.

    How to Submit Your Application via myTax Portal

    The standard method involves a digital submission via the myTax Portal, which typically takes about 15 to 20 minutes to complete if all documents are prepared.

    To guide you through the technical interface, here is the exact workflow you will encounter.

    Step 1: Logging in with CorpPass

    To begin, visit the IRAS myTax Portal (mytax.iras.gov.sg) and select “Business Tax.” You must log in using your CorpPass credentials.

    Specifically, ensure that the person logging in has been assigned the “Approver” or “Preparer” role for GST (Filing and Applications) within the CorpPass system. Without this authorization, the relevant menus will not appear. Once logged in, navigate to the menu bar, select “GST”, and then click on “Apply for GST Registration”.

    Step 2: Completing Form GST F1

    Once inside the module, you will likely be filling out Form GST F1 (Application for GST Registration). The form acts as a dynamic interview, asking for details regarding your financial year-end, turnover figures, and business activities.

    Detailed inputs required include:

    • Turnover Details: You must declare your taxable turnover.
    • Financial Year End (FYE): This determines your filing cycle (usually quarterly).
    • Industry Code (SSIC): Ensure this matches your ACRA profile.

    If you are a professional service provider or a consultant, be precise about your business description. For Koobiz clients, we handle this data entry meticulously to prevent discrepancies that could trigger an IRAS audit query.

    Step 3: Processing Time and Notification

    After submission, the standard processing time is approximately 10 working days.

    During this period, IRAS may contact you for additional information or clarification regarding your business model. Upon approval, you will receive a notification via the portal and a physical letter containing your GST Registration Number and the effective date. It is crucial to monitor your email and portal inbox during this window so you do not miss the approval notice.

    What is the Effective Date of Registration?

    Prerequisites for GST Registration and timelines
    Prerequisites for GST Registration and timelines

    The Effective Date of Registration is the specific date from which you become a taxable person and must strictly start charging GST.

    This date is legally binding and marks the boundary between your non-GST and GST eras.

    • Retrospective: Usually 1 March following the end of the calendar year.
    • Prospective: Typically the date requested, or approximately 2 months after the liability trigger date (post-July 2025 rules).
    • Voluntary: Typically the date requested or a date assigned by IRAS upon approval.

    From this exact date onwards, you must charge GST (currently 9%) on your standard-rated supplies. If you issue an invoice on the effective date without GST, you will have to absorb that tax amount yourself and pay it to IRAS.

    Claiming Pre-registration Input Tax

    GST-registered businesses can claim input tax on qualifying expenses incurred before their effective registration date.

    IRAS allows claims on:

    • Goods: Held on hand at the effective date (e.g., inventory).
    • Services: Purchased within 6 months prior to the effective date (e.g., consultancy, renovation).

    Strict documentation is required, including original tax invoices. Koobiz assists clients with these retrospective audits to maximize refunds, provided the goods haven’t been sold or consumed prior to registration.

    Special Registration Cases

    Specialized schemes exist for specific business models to simplify compliance.

    Exemption from Registration

    If your turnover exceeds S$1 million but supplies are wholly (or substantially) zero-rated (exports), you may apply for exemption. This saves administrative effort but disqualifies you from claiming input tax refunds.

    Overseas Vendor Registration (OVR)

    Overseas suppliers with global turnover >S$1 million selling >S$100,000 of digital services to Singapore consumers must register under this simplified pay-only regime.

    GST Group Registration

    Related companies can register as a single taxable group. This eliminates the need to account for GST on intra-group transactions, significantly reducing paperwork and cash flow constraints.

    Responsibilities After Registration

    Compliance involves immediate operational adjustments regarding pricing and payments.

    GST-Inclusive Pricing

    All public price displays (tags, menus, websites) must be GST-inclusive (e.g., S$109, not S$100++). Showing the breakdown is optional, but the final payable price must be clear.

    GIRO Payment Setup

    IRAS mandates GIRO for GST payments and refunds for all voluntary registrants, and strongly recommends it for compulsory registrants. Failure to set up GIRO when required can lead to penalties or cancellation of voluntary registration. Koobiz handles this setup immediately upon registration.

    Additionally, you and your clients can verify your GST registration status online to ensure all business transactions are legitimate and compliant.

    Conclusion

    Registering for GST in Singapore is more than ticking a box. It’s a transition to a stricter regulatory environment that requires precise bookkeeping and timely compliance. Whether you’re compelled to register due to growing revenue or choosing voluntary registration to optimize your tax position, accuracy is essential.

    At Koobiz, we specialize in simplifying Singapore’s corporate landscape for entrepreneurs. From determining your exact liability to handling the Form GST F1 submission and managing ongoing quarterly GST return (Form F5) filings, our team ensures your business remains compliant while you focus on growth.

    Ready to streamline your GST application? Visit Koobiz.com today to consult with our tax specialists about your Singapore incorporation and GST registration needs.

    Disclaimer: This guide is based on IRAS regulations as of January 2026. Tax laws are subject to change. Readers are advised to consult with professional tax advisors or refer to the latest IRAS publications before taking action.

  • Understanding “Subject to Prevailing GST” Meaning: Singapore Tax Guide (2026)

    Understanding “Subject to Prevailing GST” Meaning: Singapore Tax Guide (2026)

    [SUMMARIES]

    Definition: “Subject to prevailing GST” means the advertised price excludes tax; the 9% Goods and Services Tax is added at the final bill.

    Current Rate: The GST rate in Singapore is stable at 9% for 2026, based on current government announcements.

    Calculation Logic: For F&B “++” pricing, GST is calculated on the sum of the base price plus the 10% service charge.

    Business Rationale: Companies use this clause in contracts to “future-proof” agreements against potential policy changes without renegotiation.

    [/SUMMARIES]

    The phrase “subject to prevailing GST” on Singapore invoices or menus simply means the listed price excludes tax, with the current 9% Goods and Services Tax added at payment. Whether you are calculating a “++” restaurant bill or drafting future-proof contracts, understanding this term is key to accurate costing. Koobiz, your trusted partner for Singapore incorporation and tax services, explains its meaning, the stable 2026 GST rate, and the correct calculation methods.

    What Does “Subject to Prevailing GST” Mean?

    GST: The original price of $100 increases to $109.90 after tax
    GST: The original price of $100 increases to $109.90 after tax

    “Subject to prevailing GST” is a pricing condition defining that the listed cost is exclusive of tax, and the final payable amount will include the Goods and Services Tax rate effective at the specific time of supply.

    Key features include: the GST rate applied is the one effective when the transaction is completed or invoiced; the tax liability is determined at payment rather than the contract date; and any future GST increase is passed to the buyer, not absorbed by the seller. This pricing model is commonly used by hotels, higher-end restaurants, and professional service providers.

    This differs from “nett” pricing—typical in hawker centres and retail—where the displayed price is final. For international entrepreneurs working with Koobiz, understanding this distinction is fundamental to accurate and compliant financial planning in Singapore.

    The current GST rate in 2026: Is it still 9%?

    Yes, the prevailing GST rate in Singapore remains stable at 9% throughout 2026, maintaining the ceiling established after the final scheduled hike in 2024.

    To provide context, here is the timeline of recent and projected GST rate adjustments:

    Period GST Rate Status
    Before 2023 7% Historical Rate
    Jan 1, 2023 8% 1st Stage Increase
    Jan 1, 2024 9% 2nd Stage Increase
    2025 – 2030 9% Current & Stable*

    *Note: Stability is based on current government projections and is subject to economic conditions.

    Although “prevailing” suggests variability, the GST rate for 2026 is effectively fixed. Current government guidance indicates no further GST increases are expected before 2030, though policy changes may still arise through future Budgets or major economic developments.

    This stability provides a reliable planning baseline and removes the uncertainty seen during the 2023–2024 transition. Nonetheless, invoices and contracts will continue to reference the “prevailing rate” for legal accuracy. For Koobiz clients, our accounting team ensures all invoices correctly apply the 9% GST, keeping you fully compliant with IRAS GST filing requirements.

    How to calculate the final bill (The “++” Rule)

    Calculating a $100++ bill: 10% Service Charge, 9% Compounded GST, Total $119.90
    Calculating a $100++ bill: 10% Service Charge, 9% Compounded GST

    To calculate the final bill under the “++” (Plus Plus) pricing model, you must first apply the 10% service charge to the base price, and then calculate the 9% GST on that combined total.

    Many consumers and even some new business owners make the mistake of calculating the 10% service charge and the 9% GST separately on the base price. This is incorrect. In Singapore’s F&B and hotel sectors, GST is a tax on the value of the service provided, and the service charge is considered part of that value. Therefore, the tax is compounded.

    The Breakdown of “++”:

    1. First “+” (Service Charge): 10% of the menu price.
    2. Second “+” (GST): 9% of the (Menu Price + Service Charge).

    Mathematical Formula:

    Final Bill = (Base Price x 1.10) x 1.09

    Let’s illustrate this with a concrete example for 2026.

    If you order a meal listed at SGD 100++:

    • Step 1: Calculate Service Charge: $100 x 10% = $10.
      • Subtotal: $110.
    • Step 2: Calculate Prevailing GST (9%) on the Subtotal: $110 x 9% = $9.90.
    • Final Payable Amount: $100 + $10 + $9.90 = $119.90.

    If you simply added 10% and 9% to the base ($19 total), you would calculate a final bill of $119.00, which is short by $0.90. While small on a single meal, for businesses processing thousands of transactions, this calculation error can lead to significant tax filing discrepancies. Koobiz advises all F&B clients to configure their Point-of-Sale (POS) systems to adhere strictly to this compounding logic to satisfy IRAS audit requirements.

    “GST Inclusive” vs. “Subject to GST”: Visual Comparison

    “GST-inclusive” pricing shows the final amount payable upfront, while “subject to GST” displays a base price that increases at payment. This is not merely a pricing choice but an IRAS-regulated requirement.

    In general, retailers such as supermarkets and fashion stores must display GST-inclusive prices, while the “subject to GST” model is permitted mainly in the F&B and hotel sectors where service charges apply.

    Feature GST Inclusive (Nett) Subject to Prevailing GST (++)
    Industry Retail, Hawkers, Transport Hotels, Restaurants, B2B Services
    Transparency High: What you see is what you pay Low: Final price is higher than listed
    Psychology “Honest” pricing “Optical” pricing (appears cheaper)
    Calculation Price includes the 9% tax component Tax added on top of the price

    For instance, shoes priced at $109 nett generate $100 in revenue, with $9 remitted as GST. By contrast, a $100 fee quoted “subject to GST” results in a total charge of $109 to the client.

    This distinction is critical for cash flow management. For Koobiz retail clients, we help them verify their GST registration status and ensure price displays comply with GST-inclusive rules to avoid consumer protection breaches. For B2B clients, quoting fees “subject to GST” remains the standard approach to safeguard margins.

    Why do contracts still use “Prevailing Rate” if the rate is stable?

    Contracts use 'prevailing GST' to safeguard against tax hikes after 2030
    Contracts use ‘prevailing GST’ to safeguard against tax hikes after 2030

    Businesses retain the “prevailing GST” clause in long-term contracts to future-proof agreements against post-2030 legislative changes without renegotiation. While the rate is stable at 9% in 2026, leases or service retainers often span many years.

    If a contract were to state “plus 9% GST” and the rate later increased, the supplier could be forced to absorb the difference. Using “subject to prevailing GST” allows the contract to automatically reflect the legally applicable rate at invoicing, protecting margins. At Koobiz, we routinely review for this clause when drafting or vetting contracts to safeguard clients from future tax exposure.

    Time of supply rules (General application)

    The “Time of Supply” rules determine which prevailing GST rate applies, based on the earlier of the invoice date or the payment date. This tax point is decisive, regardless of when a contract was signed or work commenced.

    For example, a contract signed in December 2025 but invoiced in January 2026 is subject to the January 2026 rate of 9%. For high-volume businesses, errors in identifying the Time of Supply can result in under-declared GST. Koobiz accounting services help audit these timelines to ensure accurate and compliant GST returns.

    Tourist refunds & export exceptions

    The “subject to prevailing GST” rule mainly applies to domestic consumption, but international visitors can offset this cost through the Tourist Refund Scheme (TRS). Tourists may reclaim the 9% GST (less a handling fee) on eligible purchases above $100 from participating retailers when goods are taken out of Singapore—an important mechanism for the retail and luxury sectors.

    Likewise, B2B exports are generally zero-rated supplies, meaning exported goods are subject to 0% GST. Understanding these exceptions can deliver significant savings for both businesses and visitors.

    Real-World Case Studies: Putting It All Together

    To help you visualize how “Subject to Prevailing GST” applies in daily life and business, here are three common scenarios you might encounter in Singapore.

    Case Study 1: The Company Annual Dinner (F&B “++”)

    Scenario: You are hosting a company dinner at a hotel restaurant. The menu price is listed as $1,000++.

    The Confusion: You budget $1,190, assuming you just add 10% and 9% ($190) to the bill.

    The Reality: The restaurant charges the 10% Service Charge first ($100), creating a subtotal of $1,100. The 9% GST is then applied to this $1,100, which is $99 (not $90).

    Final Bill: $1,199.00.

    Lesson: Always account for the compounding effect when budgeting for corporate events.

    Case Study 2: The 5-Year Office Lease (Contract Clauses)

    Scenario: A startup signs a 5-year office rental agreement in 2026. The monthly rent is stated as “$5,000 subject to prevailing GST.”

    The Logic: The landlord uses this clause even though the rate is stable at 9%. If the government unexpectedly raises the GST to 10% in 2029, the startup will automatically pay $5,500 (Rent + 10%) starting that month.

    Lesson: The clause protects the landlord from absorbing future tax hikes. As a tenant, this means your costs could theoretically rise if tax laws change, without the lease being renegotiated.

    Case Study 3: The Cross-Year Consultant (Time of Supply)

    Scenario: A consultant completes a project in December 2025 but issues the invoice in January 2026.

    The Application: Even though the work was finished in 2025, the Time of Supply is triggered by the invoice date (January 2026). Therefore, the GST rate applicable is the one prevailing in January 2026.

    Lesson: While the rate is 9% in both years, this rule is critical for accurate tax filing. The consultant must declare this revenue in their 2026 GST return, not 2025.

    Conclusion

    Understanding the phrase “Subject to Prevailing GST” is more than just a math exercise; it is about navigating the legal and financial norms of Singapore’s vibrant economy. In 2026, while the rate is stable at 9%, the implications of calculation methods and contractual phrasing remain vital for financial health. Whether you are calculating the cost of a business dinner or drafting a ten-year lease agreement, clarity on these terms prevents unexpected costs and ensures compliance.

    About Koobiz

    Navigating Singapore’s tax and corporate landscape can be complex, but you don’t have to do it alone. Koobiz is your premier partner for Singapore company incorporation, corporate secretary services, and opening corporate bank accounts in Singapore. Our team of experts also provides comprehensive accounting, tax, and auditing services, ensuring your business stays compliant with IRAS regulations while optimizing your tax position.

    Ready to start or grow your business in Singapore? Visit koobiz.com today for a consultation.

    Disclaimer: This guide is provided for general informational purposes only and does not constitute professional legal or tax advice. While all information is accurate based on IRAS announcements as of January 2026, tax regulations are subject to change. Readers should consult with IRAS or a qualified tax professional at Koobiz for advice specific to their business situation.